


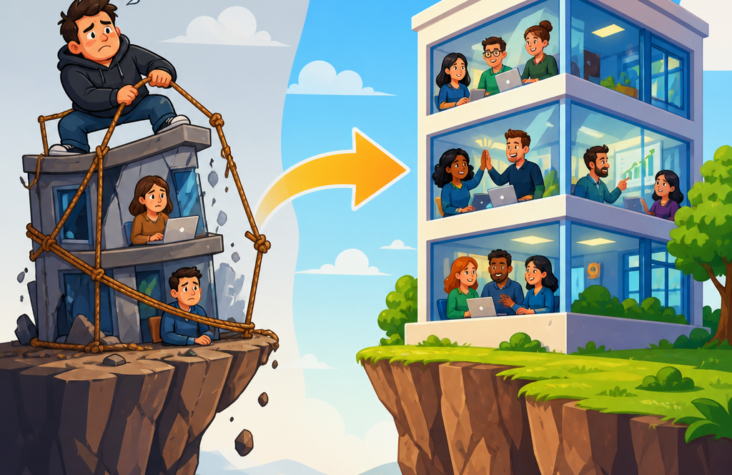
What Founder Dependency Does to Enterprise Value
Founder dependency is one of the fastest ways to reduce enterprise value because buyers do not pay premium multiples for companies that rely on one person to make sales, solve problems, approve decisions, manage relationships, and hold the culture together. In valuation and deal structuring, founder dependency is the concentration of operational, commercial, and institutional risk in the owner. Enterprise value is the total value a buyer assigns to the company as a transferable asset, usually based on EBITDA, recurring revenue quality, growth durability, and risk. Risk and legal impact on value sit at the center of that equation because any company that cannot function smoothly without its founder creates uncertainty, and uncertainty compresses multiples.
I have seen this issue surface in founder-led companies across services, distribution, e-commerce, software, and family-owned businesses. The pattern is predictable. Revenue may look healthy, margins may even be attractive, but once a buyer starts diligence, the same questions appear. Who owns the customer relationships? Who approves pricing? Who understands the financial story? Who can operate the business if the founder leaves after closing? If the honest answer is “the founder,” value drops. Sometimes the buyer lowers the multiple. Sometimes more of the purchase price gets pushed into an earnout. Sometimes the deal becomes an acqui-hire in disguise. Sometimes the transaction dies completely.
This hub article explains what founder dependency does to enterprise value and why it matters in risk and legal impact on value. It also frames the major subtopics founders need to understand: operational concentration risk, customer concentration around the owner, key-person legal exposure, contract fragility, intellectual property ownership, HR and compliance issues, financial reporting dependence, and transition structure. If you want better valuation outcomes, stronger buyer confidence, and more negotiating leverage, founder dependency has to be treated as a solvable value problem, not a personality trait.
Why buyers discount founder-dependent businesses
Buyers acquire future cash flow, not founder heroics. A founder-dependent company may have impressive historical performance, but enterprise value reflects the probability that performance will continue after closing. When the founder is central to production, sales, hiring, culture, banking relationships, and strategic direction, the buyer sees unstable future earnings. In practice, that means the company is less transferable, less financeable, and less scalable.
Private equity firms, strategic acquirers, search funds, and independent sponsors all evaluate this risk differently, but they all evaluate it. A private equity buyer usually asks whether the management team can support leverage and execute a growth plan without daily founder involvement. A strategic buyer asks whether customers, employees, and systems will survive integration if the founder exits. A bank underwriting acquisition debt asks whether the revenue stream is durable enough to support repayment. In each case, founder dependency weakens confidence.
This is why two businesses with similar revenue and EBITDA can produce very different outcomes. A company with a documented operating model, diversified customer ownership, enforceable contracts, and a real leadership bench may command a meaningfully higher multiple than a founder-centric peer. In lower middle-market transactions, the spread can be material. A business at 4.5x EBITDA versus 6.5x EBITDA on $3 million of EBITDA is a $6 million difference in enterprise value before you even debate structure.
Operational risk: when the founder is the system
The first value destroyer is operational dependence. If the founder is the escalation point for every problem, the business does not have systems; it has memory. Buyers look for repeatable processes, clear reporting lines, standard operating procedures, pricing discipline, delegated authority, and measurable accountability. When those are missing, the company becomes harder to diligence and harder to transfer.
A real-world example is common in founder-led agencies and service firms. The owner still approves every proposal, joins every major client call, resolves every staffing dispute, and personally reviews deliverables. Revenue may be recurring, but the actual operating engine lives in the founder’s calendar. Buyers usually respond in one of three ways. They discount value because replacing the founder will require cost and time. They require a longer transition agreement. Or they structure the deal with contingent payments tied to retention and performance.
This is also where legal risk starts to compound. Weak operations create undocumented exceptions, side arrangements, unclear authority, and inconsistent compliance. A founder may verbally approve payment terms for one customer, hiring terms for one executive, or service changes for one key account. Those “tribal” decisions often never make it into contracts, SOPs, or policy manuals. During diligence, that gap becomes a risk issue, not just an efficiency issue.
Customer concentration around the founder
One of the most overlooked forms of concentration risk is not customer concentration by revenue, but customer concentration by relationship ownership. A buyer may see twenty well-diversified accounts and still worry if the founder personally controls all twenty relationships. That means retention risk is hidden in plain sight.
In founder-driven businesses, key customers often buy because they trust the owner’s judgment, responsiveness, or technical expertise. If those customers perceive the sale as the founder leaving, they may reevaluate the relationship. Buyers know this. That is why they ask for customer call lists, account ownership maps, retention histories, and transition plans.
From a legal and structuring perspective, this issue can alter the entire deal. Buyers may insist on non-compete and non-solicit provisions with longer durations and broader scope. They may require the founder to sign an employment or consulting agreement post-close. They may hold back proceeds in escrow or create earnouts tied to customer retention. In practical terms, the market is telling you that relationship transferability is part of value.
Key-person risk and the legal impact on value
Key-person risk sits at the center of risk and legal impact on value because founder dependency often creates legal exposure that is invisible until diligence. If the founder is the person who holds licenses, certifications, regulatory approvals, banking signatory authority, or unique contractual permissions, the buyer has to determine whether those rights transfer automatically, require consent, or disappear at closing.
Examples are everywhere. In professional services, licenses may sit with individuals rather than entities. In government contracting, specific personnel qualifications may support eligibility. In healthcare, compliance frameworks may rely on designated responsible parties. In distribution, lender relationships and guarantees may be founder-specific. In software, code access, admin credentials, and vendor approvals may rest with the founder’s personal accounts. If those dependencies are not formalized within the company, value is impaired.
These issues increase legal fees, extend diligence, and create leverage for retrading. Buyers use purchase agreement language, indemnities, reps and warranties, holdbacks, and transition covenants to cover the uncertainty. Founders should read that market feedback correctly. The problem is not that buyers are difficult. The problem is that the business was never fully separated from the founder.
Contracts, change-of-control clauses, and assignability risk
Contract risk is one of the clearest legal channels through which founder dependency affects valuation. Many founder-led companies have customer, vendor, partner, and landlord agreements that were negotiated personally by the owner. Those contracts often contain change-of-control provisions, consent requirements, service-level assumptions, or key-person expectations that become problematic in a sale.
If revenue-producing contracts are non-assignable without consent, buyers discount certainty. If major customers can terminate on a sale, buyers model churn risk. If supplier terms were extended based on founder relationships rather than documented credit quality, margin durability becomes questionable. If the founder signed side letters, email commitments, or verbal modifications, legal diligence becomes slower and more adversarial.
This is why contract hygiene belongs in every valuation conversation. Buyers want a business whose commercial obligations are entity-based, enforceable, centralized, and transferrable. Founder dependency undermines all four. A disciplined contract audit before going to market often creates immediate value because it removes ambiguity that would otherwise surface late and damage leverage.
Intellectual property and ownership gaps
In many founder-dependent companies, intellectual property is also founder-dependent. That sounds extreme until diligence begins. Buyers routinely find trademarks registered personally, domains owned outside the operating entity, software developed by contractors without proper assignment agreements, and brand assets controlled through the founder’s personal email or payment accounts.
Those gaps matter because enterprise value depends on the buyer receiving the assets necessary to operate and defend the business after closing. If ownership is unclear, the buyer is not really buying a complete company. The issue is especially serious in SaaS, digital marketing, e-commerce, media, and product businesses where code, content, data, and brand are core assets.
Strong buyers will require assignment cleanup before closing. Conservative buyers will reduce price or increase indemnity demands. Sophisticated buyers may question whether the founder intentionally blurred ownership, which can affect overall trust in management representations. Clean IP ownership is not administrative housekeeping. It is a direct driver of value credibility.
Employment, compliance, and culture risk
Founder dependency often masks people risk. In many businesses, employees stay because of loyalty to the founder rather than loyalty to the institution. When that happens, retention risk becomes a valuation issue and a legal issue. Buyers worry about post-close departures, wage and hour inconsistencies, undocumented compensation promises, misclassified contractors, and informal HR practices.
If the founder handles hiring personally, negotiates exceptions informally, or makes verbal bonus promises, diligence becomes harder. If no one else can recruit, onboard, evaluate, or motivate the team, buyers assume disruption. If culture is defined only by the founder’s presence rather than by norms, systems, and leaders, buyers see fragility.
This is one reason founders should invest early in management structure, written employment terms, incentive plans, and documented HR processes. A transferable culture increases value because it suggests the organization can maintain performance through ownership change. A personality-driven culture depresses value because it raises the probability of operational leakage right after closing.
How founder dependency changes deal structure
Even when founder dependency does not kill a deal, it changes the way buyers pay. That is the most practical lens for understanding its impact. High dependency usually means less cash at close, more earnout, more rollover pressure, longer employment obligations, tighter restrictive covenants, and more aggressive indemnity language.
| Founder Dependency Level | Typical Buyer Response | Likely Value Impact |
|---|---|---|
| Low | Higher upfront cash, shorter transition, cleaner reps | Supports premium multiple |
| Moderate | Partial earnout, retention conditions, broader diligence | Moderate multiple pressure |
| High | Heavy earnout, escrow, long stay requirement, key-person protections | Compressed multiple and lower certainty |
This is why founders should not judge a deal solely by headline valuation. A business quoted at 7x EBITDA with aggressive contingencies may be economically worse than a 6x offer with strong cash certainty. Founder dependency gives buyers justification to shift risk back to the seller. Reducing dependency restores leverage.
How to reduce founder dependency before a sale
The fix is strategic and measurable. Start by mapping every critical function the founder touches: sales, pricing, delivery, hiring, banking, vendor management, compliance, customer escalation, and forecasting. Then assign ownership, document process, and build redundancy. If a buyer asked, “Who runs this if the founder disappears for ninety days?” you should have a credible answer for each function.
Second, transfer relationships. Put executives and account leaders in front of customers, lenders, suppliers, and referral partners. Third, centralize contracts, permissions, and IP inside the entity. Fourth, build a real reporting cadence so buyers can trust performance without founder interpretation. Fifth, address legal and compliance exceptions before diligence forces the issue.
For founders serious about preparation, resources like The Entrepreneur’s Exit Playbook can help frame how readiness affects leverage and valuation: https://amzn.to/3NOnNVH. More guidance on deal readiness and sell-side planning is also available through Legacy Advisors. Those resources matter because founder dependency is rarely solved by instinct alone. It requires a plan.
What this hub means for the broader risk and legal impact on value topic
Founder dependency is the hub issue because it connects directly to every major subtopic in risk and legal impact on value. It shapes contract risk, customer retention risk, key-person exposure, employment risk, IP ownership, compliance quality, diligence outcomes, and final deal structure. If you are building a business to sell, this is not a side issue. It is one of the core determinants of whether your company is valued as a scalable asset or as an unstable extension of you.
The practical takeaway is simple. Buyers pay more for businesses that are documented, delegated, defensible, and transferable. They pay less for businesses built on founder memory, founder relationships, founder approvals, and founder rescue missions. If you want stronger enterprise value, start removing yourself from the center of the machine now. Audit the legal dependencies, transfer the relationships, institutionalize the knowledge, and build the team. That work does more than reduce risk. It turns your company into something the market can trust, finance, and pay a premium for. If this topic is relevant to your situation, review the related resources on Legacy Advisors and study the framework in The Entrepreneur’s Exit Playbook. The best time to solve founder dependency is before a buyer prices it for you.
Frequently Asked Questions
What does founder dependency mean in the context of enterprise value?
Founder dependency means the business depends heavily on the owner to function, grow, and maintain stability. In practical terms, the founder is often the primary rainmaker, key decision-maker, relationship manager, problem solver, and cultural anchor all at once. That concentration of responsibility creates risk because the company’s performance is tied to one individual rather than to systems, management depth, and repeatable processes. From a buyer’s perspective, that is not just an operational issue; it is a valuation issue.
Enterprise value reflects what a buyer believes the company is worth as a transferable asset. A transferable asset should continue performing even when ownership changes. If the founder must stay involved for sales to close, employees to perform, clients to remain loyal, or major decisions to get made, then the business is less transferable. Buyers will usually respond by lowering the valuation multiple, increasing diligence scrutiny, or changing the deal structure to protect themselves from the risk of underperformance after closing.
In short, founder dependency reduces value because it increases uncertainty. The more a company relies on one person to hold together revenue, execution, and trust, the less confidence a buyer has that future cash flow will survive a transition. That confidence gap is exactly where enterprise value gets compressed.
Why do buyers and investors discount companies that rely too much on the founder?
Buyers and investors pay for durable earnings, predictable growth, and low transition risk. When too much of the company’s success sits with the founder, all three of those value drivers are weakened. Revenue may appear strong on paper, but if key customers buy because of personal loyalty to the founder, that revenue becomes fragile. Operations may look efficient, but if the founder is personally solving exceptions, approving key actions, and keeping teams aligned, then the company may be less stable than its financial statements suggest.
This is why founder dependency often leads to discounted valuation multiples. A buyer is not only evaluating historical results; they are underwriting future performance. If there is a meaningful chance that customers, employees, suppliers, or managers will struggle once the founder steps back, that risk has to be priced in. Sometimes that pricing shows up as a lower multiple. Other times it appears through earnouts, seller financing, holdbacks, or employment agreements designed to keep the founder involved longer than originally expected.
Investors think the same way, even if their time horizon is different. They want scalable businesses, not founder-powered machines. A company that requires the founder’s constant intervention is harder to grow, harder to professionalize, and harder to eventually sell. In the market, risk and value move in opposite directions. When founder dependency rises, perceived risk rises, and enterprise value tends to fall.
How does founder dependency show up during valuation and due diligence?
Founder dependency becomes visible in due diligence through patterns that signal the business is not truly independent of its owner. Buyers will look at customer concentration and ask whether major accounts are loyal to the company or to the founder personally. They will examine the sales pipeline to see whether deal flow comes from a repeatable system or from the founder’s individual network. They will interview managers to understand who really makes decisions, who owns relationships, and whether leadership can operate without the founder in the room.
It also appears in more subtle ways. If pricing decisions, hiring approvals, vendor negotiations, product exceptions, dispute resolution, and strategic planning all flow through one person, diligence teams will notice. If there is limited documentation, weak reporting, inconsistent delegation, or no clear second layer of leadership, the buyer will likely conclude that the business has hidden continuity risk. Even a healthy EBITDA margin can be viewed differently once a buyer realizes that the founder is effectively performing multiple executive roles without replacement infrastructure.
As a result, founder dependency often influences both valuation and deal terms. A buyer may reduce the headline price, require a longer transition period, tie part of the purchase price to post-close performance, or insist on retention plans for key team members. The issue is not whether the founder is talented; in many cases, that is exactly the problem. The more the company depends on extraordinary founder involvement, the harder it is for a buyer to treat the business as a stable, transferable asset.
What are the most common signs that founder dependency is hurting business value?
Some warning signs are obvious. If the founder is the top salesperson, the final decision-maker, the keeper of major customer relationships, and the person employees turn to for every escalation, the business is likely overdependent. If the founder cannot take meaningful time away without performance dropping, that is another clear indicator. Buyers also pay close attention when no one on the leadership team can confidently explain strategy, own outcomes, or operate independently.
Other signs show up in the company’s structure and habits. There may be weak delegation, limited process documentation, unclear roles, or a lack of management accountability. Important information might live in the founder’s head instead of in systems, dashboards, contracts, or standard operating procedures. The company may also have inconsistent sales results because business development depends on the founder’s personal energy, reputation, or network rather than on a managed pipeline and trained team.
Cultural dependency is another major signal. If the founder is the person who resolves internal conflict, reinforces standards, motivates the team, and protects client trust, then the company may not have an institutional culture strong enough to survive transition. None of these signs automatically make a business unsellable, but they do affect how buyers view risk. The more these issues are present, the more likely it is that enterprise value will be reduced through lower multiples, tighter terms, or both.
How can a founder reduce dependency and protect or increase enterprise value before a sale?
The goal is to make the business perform as a company rather than as an extension of the founder. That starts with transferring knowledge, authority, and relationships into the organization itself. Founders can build value by strengthening the leadership team, clarifying decision rights, documenting key processes, and creating reporting systems that make performance visible without constant owner involvement. When responsibilities are distributed and measurable, buyers gain confidence that the company can continue operating smoothly after a transaction.
Commercial transferability matters just as much. The business should not rely on the founder alone to generate demand or retain top accounts. Sales should be supported by a process, a team, customer data, and account ownership that extends beyond the founder’s personal relationships. Key clients should know and trust multiple people inside the company. Supplier relationships, banking contacts, and strategic partnerships should also be institutionalized so continuity does not depend on one individual’s presence.
Finally, founders should treat dependency reduction as a value-creation initiative, not just a succession exercise. A buyer will pay more for a business with management depth, documented operations, recurring revenue quality, and a culture that can sustain itself. Ideally, this work begins well before a sale process, because it takes time to prove that changes are real and durable. When a company can show that performance is repeatable without day-to-day founder rescue, buyers are more likely to view earnings as transferable, risk as lower, and enterprise value as stronger.