

How Insurance Indemnities and Escrows Shape Price Negotiations
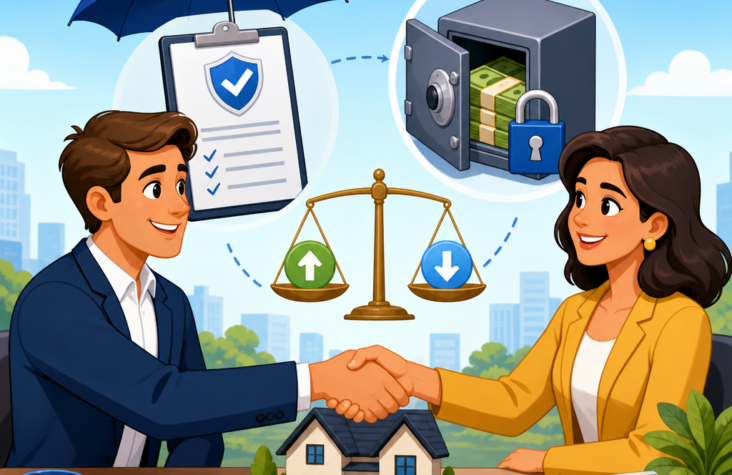
Insurance indemnities and escrows shape price negotiations because they determine who bears post-closing risk, how much cash the seller actually receives at closing, and how confidently a buyer can pay a premium valuation. In mergers and acquisitions, headline price is only one part of economic value. The real deal is the combination of purchase price, indemnity structure, escrow size, survival periods, deductible thresholds, and whether representation and warranty insurance shifts risk away from the parties. For founders, business owners, and investors, understanding risk and legal impact on value is essential because two offers with the same stated price can produce dramatically different outcomes once indemnities and escrows are layered in.
At a basic level, an indemnity is the seller’s obligation to reimburse the buyer if certain losses arise after closing. Those losses usually relate to breaches of representations and warranties, pre-closing tax liabilities, compliance failures, litigation, employee claims, or customer contract problems. An escrow is a portion of the purchase price held back by a third party for a defined period to satisfy those indemnity claims if they arise. Representation and warranty insurance, often called RWI, is an insurance policy that can cover many losses from breaches of reps and warranties, reducing the need for large escrows or broad seller exposure. These concepts matter because they directly affect valuation, negotiation leverage, and net proceeds. As discussed across the Legacy Advisors perspective on exit planning, buyers do not just buy earnings; they buy confidence, transferability, and low-risk cash flow.
Risk and legal impact on value sits at the center of modern deal structuring. A business with clean contracts, documented compliance, accurate financials, assignable intellectual property, and limited legal exposure can often command a higher multiple and lighter indemnity package. A business with unsettled tax issues, customer concentration, weak employment documentation, or unresolved litigation may still sell, but often at a lower effective price once escrows and indemnity protections are imposed. That is why this article serves as a hub for the broader subtopic. If you are preparing to sell a company, evaluate a Letter of Intent, or compare strategic and financial buyers, you need a working understanding of how legal risk gets priced into the deal.
Why indemnities change the real purchase price
Indemnities affect price because they convert uncertain future risk into a present negotiation over dollars. Buyers start with a simple question: if a hidden problem appears after closing, who pays? Sellers naturally want a clean exit and maximum cash at close. Buyers want protection against losses they cannot fully diligence before signing. The negotiated answer changes enterprise value in practice, even if the top-line purchase price stays constant.
Consider a $25 million acquisition. Offer A is $25 million with 95 percent paid at closing, a 10 percent escrow, and a seller indemnity cap of 15 percent of purchase price for general reps. Offer B is also $25 million, but it uses representation and warranty insurance, has a 1 percent escrow only for limited fundamental matters, and a much narrower indemnity package. On paper, the price is the same. Economically, it is not. In Offer A, the seller may wait 12 to 24 months to access a meaningful portion of proceeds and faces continuing claim risk. In Offer B, the seller has more certainty, more immediate liquidity, and less tail exposure. Buyers know this, which is why indemnities become a pricing lever.
In deals I have seen structured well, the buyer does not always reduce the stated price when legal risk is elevated. Instead, the buyer often preserves the headline number while increasing the escrow, broadening indemnity language, extending survival periods, or creating a special indemnity for a known issue. That distinction matters. Founders often focus too heavily on the headline valuation and not enough on what portions are at risk. The practical lesson is direct: effective purchase price equals signed price minus retained risk, held-back cash, legal friction, and claim exposure.
How escrows create leverage in deal structuring
Escrows are one of the clearest ways risk and legal impact on value shows up in documented economics. An escrow typically holds back a percentage of the purchase price, often between 5 and 15 percent in lower middle-market transactions, though the number varies by industry, buyer type, and diligence quality. Buyers prefer escrows because they provide a ready source of funds if indemnity claims arise. Sellers dislike them because they reduce immediate liquidity and signal distrust.
The size and duration of the escrow often reflect diligence confidence. When books are clean, tax filings are current, customer contracts are organized, and no major red flags appear, escrows tend to be smaller and shorter. When a business has unresolved revenue recognition issues, independent contractor misclassification risk, regulatory uncertainty, or weak documentation around intellectual property ownership, the escrow gets bigger. The buyer is not only protecting itself; it is also quantifying doubt.
Escrows also influence negotiation psychology. A buyer may say, “We will hold the price if you agree to a larger escrow.” That sounds seller-friendly, but it is really a repricing mechanism. If the seller has multiple bidders, the seller can push back and compare structures, not just price. That is one reason running a competitive process matters. When only one buyer is at the table, escrow demands often expand because there is less market pressure to stay seller-friendly.
| Deal Term | Seller-Friendly Structure | Buyer-Friendly Structure | Impact on Effective Value |
|---|---|---|---|
| General escrow | 1% to 5% for 12 months | 10% to 15% for 18 to 24 months | More holdback lowers immediate seller proceeds |
| Indemnity cap | 5% to 10% of price | 15% to 25% of price | Higher cap increases seller tail risk |
| Basket or deductible | True deductible with higher threshold | Tipping basket with low threshold | Lower threshold increases claim frequency |
| RWI usage | Policy replaces broad seller exposure | No policy, direct seller recourse | Insurance can preserve cash at close |
| Special indemnity | Narrow, time-limited issue | Broad, uncapped known-risk protection | Specific risks can silently reduce price |
Where insurance changes the negotiation
Representation and warranty insurance has changed M&A negotiations, especially in transactions where private equity firms, sophisticated strategics, or experienced founder-sellers want cleaner outcomes. RWI allows a buyer to make claims against an insurance policy for many breaches of reps and warranties rather than pursuing the seller directly. The result can be lower escrows, narrower seller indemnities, and more cash at closing. In competitive auctions, a buyer willing to use insurance can become more attractive even without raising the nominal purchase price.
That said, insurance does not eliminate risk. Policies have exclusions, retention amounts, underwriting scrutiny, and policy limits. Known issues uncovered in diligence are usually excluded. For example, if diligence reveals an unresolved sales tax nexus issue in multiple states, the insurer will not likely cover that exposure. Instead, the buyer may demand a special indemnity or targeted escrow for that issue. Insurance works best for unknown breaches, not problems already identified.
Insurance also introduces a cost allocation question. Who pays the premium? In many current-market deals, the buyer pays or the cost is split, but the answer is negotiable. Premiums commonly run around 2.5 to 4 percent of policy limits, with underwriting fees and legal review layered on. On a $20 million policy, that cost is material. Still, if paying for insurance allows a seller to reduce a $3 million escrow to a $250,000 holdback, many sellers will gladly accept the trade.
This is where the broader Valuation and Deal Structuring topic becomes practical. Legal structure affects not only downside risk but saleability. A founder comparing offers should ask: does this bidder rely on insurance, direct recourse, or both? What are the exclusions? What claims survive? What stays in escrow and why? Those answers often matter more than another quarter turn on the EBITDA multiple.
Key indemnity terms that quietly move millions
Most founders focus on price and maybe earn-out structure. Sophisticated buyers focus just as carefully on indemnity mechanics. These mechanics can quietly shift millions of dollars in exposure. Four concepts matter most: caps, baskets, survival periods, and carve-outs.
An indemnity cap limits the seller’s liability for certain claims. General reps might be capped at 10 percent of purchase price, while fundamental reps, such as authority, title to shares, and sometimes taxes, may have a much higher cap or be effectively uncapped. Buyers push for broader exceptions to the cap; sellers push to confine exposure. A lower cap generally supports higher effective seller value because it limits tail liability.
A basket sets the threshold for claims. With a true deductible, the buyer absorbs losses until the threshold is reached, then recovers only amounts above it. With a tipping basket, once losses exceed the threshold, the buyer can recover from the first dollar. That distinction is economically significant. A $250,000 tipping basket is much more buyer-friendly than a $250,000 deductible.
Survival periods define how long reps and warranties remain enforceable after closing. General reps may survive 12 to 18 months; tax reps often survive through the statute of limitations; fundamental reps may survive longer. Longer survival increases seller risk and usually justifies either higher price certainty elsewhere or tighter claim standards.
Carve-outs are exceptions. Fraud is almost always carved out. Buyers may try to carve out specific known issues, environmental liabilities, wage-and-hour matters, or cybersecurity incidents from general limitations. Sellers should view every carve-out as a direct valuation question, because once a matter is carved out and separately indemnified, the buyer has effectively found a way to preserve price while still lowering economic certainty.
Common legal risks that drive heavier escrows and tougher indemnities
Not all risk is viewed equally. Some legal issues consistently produce tougher deal terms because they are hard to quantify, expensive to remediate, or likely to generate third-party claims. In lower middle-market and mid-market M&A, the most common triggers are tax exposure, employment classification problems, customer contract assignability issues, data privacy gaps, and incomplete intellectual property ownership.
Tax issues matter because unpaid sales tax, payroll tax, or nexus exposure can survive the sale and create substantial assessments. Employment issues matter because wage-and-hour disputes, contractor misclassification, or undocumented bonus obligations can produce recurring claims. Customer contract issues matter because a buyer paying for recurring revenue wants assurance that key agreements survive a change of control. Data privacy matters because a business collecting customer information without documented compliance can inherit regulatory risk. IP ownership matters because buyers will not pay premium multiples for software, content, or proprietary processes if the company cannot prove it owns them.
These are not abstract concerns. They are the exact issues that appear in diligence request lists and lead to revised purchase agreements. If your business has one of these risks, the market often responds with a larger escrow, a special indemnity, lower cash at close, or all three. That is why preparation matters. The same company can be worth meaningfully more six months after legal cleanup than it is today.
How founders should prepare before price talks begin
The best way to improve price negotiations is to reduce uncertainty before the buyer prices it for you. That means cleaning up legal risk before the Letter of Intent stage whenever possible. Review customer contracts for assignability and termination rights. Confirm all tax filings are current. Tighten employment agreements, restrictive covenants, and contractor documentation. Make sure IP assignment agreements are signed and accessible. Document compliance in regulated or data-sensitive industries.
This is exactly why founders benefit from structured exit planning. The most successful exits are not reactive. They are reverse engineered. If you wait until confirmatory diligence for the buyer to find missing documents, old disputes, or compliance gaps, you lose leverage. If you identify them early, fix what can be fixed, and disclose what must be disclosed with context, you keep more control over structure.
Founders should also model proceeds based on multiple structure scenarios. Do not ask only, “What is my valuation?” Ask, “What do I receive at closing, what is held back, what is insured, what is contingent, and what survives?” That is the practical framework behind risk and legal impact on value. For deeper preparation on this thinking, The Entrepreneur’s Exit Playbook offers a useful companion resource for founders planning ahead: https://amzn.to/3NOnNVH.
Why this topic is the hub for risk and legal impact on value
Insurance indemnities and escrows shape price negotiations because they are the mechanism through which legal risk becomes economic reality. They connect diligence quality, contract strength, compliance maturity, and buyer confidence directly to cash proceeds. That makes this page the natural hub for the broader risk and legal impact on value conversation under Valuation and Deal Structuring.
The core takeaway is simple. A business is not valued only on EBITDA, revenue growth, or strategic fit. It is also valued on how safely those earnings can be transferred. Cleaner legal infrastructure supports smaller escrows, narrower indemnities, and stronger net proceeds. Messier situations invite holdbacks, special indemnities, longer survival periods, and lower effective value. If you are serious about maximizing your exit, start treating legal cleanup and risk allocation as price issues, not postscript issues.
Use this article as your foundation, then continue evaluating related topics through the Legacy Advisors perspective at https://legacyadvisors.io. Review your contracts, pressure-test your diligence readiness, and compare offers based on structure, not headlines. The founder who understands indemnities, insurance, and escrows does not just negotiate harder. That founder negotiates smarter, protects value, and walks away with more of the deal they worked so hard to build.
Frequently Asked Questions
1. Why do insurance indemnities and escrows have such a big impact on price negotiations in M&A deals?
Insurance indemnities and escrows matter because they directly affect the true economics of a transaction, not just the headline purchase price. A seller may focus on the top-line number, but a buyer evaluates the entire risk-adjusted package: how much cash is paid at closing, how much is held back in escrow, what claims can be brought after closing, how long those claims survive, and whether representation and warranty insurance is available to absorb part of the post-closing exposure. In practice, two deals with the same nominal purchase price can have very different values to both sides depending on these terms.
From the buyer’s perspective, indemnities and escrows are tools for allocating uncertainty. If the target business has potential tax issues, compliance concerns, customer concentration risk, or financial statement questions, the buyer may seek broader indemnification rights or a larger escrow to ensure there is a practical source of recovery if those risks materialize after closing. That risk protection can make a buyer more comfortable paying a stronger valuation. By contrast, if the seller insists on very limited indemnity obligations and minimal holdbacks, the buyer may reduce the purchase price to compensate for taking on more uncovered risk.
From the seller’s perspective, indemnity structure determines how much of the deal value is actually certain and immediately realizable. A large escrow or expansive indemnity package can turn part of the purchase price into contingent consideration in everything but name. Even if the headline number looks attractive, a seller cares deeply about how much money is received at closing, how quickly escrowed funds are released, and how likely it is that post-closing claims will erode total proceeds. That is why indemnities and escrows are often central battlegrounds in negotiations: they shape not only legal risk allocation, but also the practical certainty of value.
2. How does an escrow influence what a seller really receives at closing?
An escrow is a portion of the purchase price that is withheld at closing and deposited with a third party for a specified period to secure the seller’s indemnification obligations. Economically, that means the seller does not receive full access to the entire negotiated price on day one. Instead, a part of the consideration remains restricted until the escrow period ends or claims are resolved. This can materially change the seller’s net proceeds, liquidity, and view of the deal’s attractiveness.
For example, if a transaction has a $50 million purchase price but includes a 10% indemnity escrow, the seller may only receive $45 million at closing, with $5 million tied up for months or even longer. That holdback has a real cost. The seller loses immediate use of the funds, may face uncertainty about whether the escrow will be released in full, and may need to account for the possibility that buyer claims will reduce the final amount recovered. In competitive sale processes, sellers often compare bids not only by price, but by how much money is placed in escrow and for how long.
Escrow size also affects negotiating leverage. A buyer may argue that a meaningful escrow is necessary because indemnification rights are only valuable if there is a readily available recovery source. A seller, however, may counter that an oversized escrow effectively shifts excessive risk back to the seller and undermines the certainty expected in a sale. As a result, parties often negotiate escrow amount, release mechanics, claim procedures, and carve-outs in great detail. These terms can be as economically important as a price adjustment because they determine whether a portion of the agreed value is truly paid, merely deferred, or potentially forfeited.
3. What is the relationship between indemnity structure and the purchase price a buyer is willing to pay?
Indemnity structure and purchase price are closely linked because buyers price risk. When indemnification protections are robust, buyers may be willing to offer a higher valuation since they have recourse if representations prove inaccurate or if specified liabilities emerge after closing. Stronger indemnity rights reduce uncertainty and lower the buyer’s downside exposure. In that setting, the buyer can justify paying more because the seller is retaining a larger share of post-closing risk.
On the other hand, when indemnities are heavily seller-friendly, the buyer may respond by lowering the offer price. This is especially common when there are short survival periods, narrow definitions of recoverable losses, high deductible thresholds, low caps on liability, or minimal escrow support. If the buyer believes there is meaningful risk but little practical ability to recover later, it will typically seek compensation up front through a lower purchase price. In effect, risk that is not covered contractually gets priced into the valuation model.
This relationship explains why indemnity negotiations are rarely just legal fine print. They are part of the pricing discussion itself. A seller asking for a premium valuation while also demanding very limited indemnity exposure may face resistance because the buyer sees a mismatch between price and protection. Conversely, if a seller offers a clean and well-supported indemnity package, especially in a business with more complex diligence issues, that can help preserve or improve valuation. The market often treats price and indemnity terms as interchangeable levers: if one side wants more certainty in one area, the other side usually seeks compensation somewhere else in the deal structure.
4. How do survival periods, baskets, deductibles, and caps affect negotiation leverage?
These provisions define the scope and practicality of post-closing indemnification, so they strongly influence the balance of risk between buyer and seller. Survival periods determine how long representations, warranties, and covenants remain enforceable after closing. A longer survival period gives the buyer more time to discover and bring claims, which is especially important for issues that may not become visible immediately, such as tax matters, accounting irregularities, or compliance failures. A shorter survival period favors the seller by cutting off exposure sooner and increasing certainty around final proceeds.
Baskets and deductibles govern when losses become recoverable. In many deals, the seller is not liable for small claims unless aggregate losses exceed a negotiated threshold. A true deductible means the buyer can only recover amounts above that threshold, while a tipping basket may allow recovery from the first dollar once the threshold is crossed. These concepts matter because they determine whether the indemnity regime covers only major problems or also captures a series of smaller losses that add up over time. Sellers prefer higher baskets and deductibles to avoid nuisance claims; buyers prefer lower thresholds to preserve meaningful recourse.
Caps place a maximum limit on indemnification liability, often as a percentage of the purchase price. A low cap can substantially protect the seller and increase certainty of proceeds, while a higher cap gives the buyer broader financial protection if serious problems emerge. Certain matters, such as fraud, fundamental representations, or specific identified risks, are often carved out from standard caps or given separate limits. These carve-outs become intensely negotiated because they can expose the seller to much larger liability than the general indemnity framework suggests.
Taken together, these provisions are core pricing tools. If the seller wants a low cap, short survival period, and high basket, the buyer may push for a lower purchase price or a larger escrow. If the buyer accepts a seller-friendly indemnity package, it will often expect compensation elsewhere in the economics. That is why leverage on these technical points often tracks directly with auction dynamics, quality of diligence, market conditions, and the perceived risk profile of the target company.
5. How does representation and warranty insurance change the role of indemnities and escrows in price negotiations?
Representation and warranty insurance, often called R&W insurance, can significantly reshape negotiations by shifting some post-closing risk away from the seller and onto an insurer. In a traditional private M&A deal, the buyer relies heavily on the seller’s indemnity obligations and a corresponding escrow as a source of recovery. When insurance is introduced, the buyer may be able to recover certain losses through the policy instead of pursuing the seller directly. That can reduce the need for a large escrow and make the transaction more attractive to a seller seeking a cleaner exit.
For sellers, this can be especially valuable in competitive processes because it may allow them to market the deal as having limited post-closing exposure. A bid with a lower escrow and narrower seller indemnity obligations can be more appealing even if the purchase price is similar to competing offers. For buyers, insurance can support a higher bid by reducing concern that unknown breaches will be unrecoverable. In other words, insurance can help bridge the gap between a seller wanting deal certainty and a buyer wanting protection.
That said, R&W insurance does not eliminate negotiation over risk allocation. Policies contain exclusions, retention amounts, coverage limits, underwriting requirements, and claim procedures. Known issues identified in diligence are often excluded from coverage, which means those risks still need to be addressed through specific indemnities, purchase price adjustments, or escrows. In addition, someone must bear the cost of the premium, and that expense itself can become part of the economic negotiation. Buyers and sellers also negotiate whether the seller remains liable for certain matters outside the policy, such as fraud, fundamental representations, taxes, or specifically disclosed problem areas.
The practical effect is that insurance changes the structure of the conversation rather than making it disappear. It often reduces friction around general indemnities and can support stronger valuations by giving buyers more confidence. But it does not replace careful drafting or eliminate the need to negotiate who