

What Belongs in a Virtual Data Room Before Buyer Access Begins
A virtual data room is the control center of a serious sale process, and if it is not organized before buyer access begins, founders lose leverage fast.
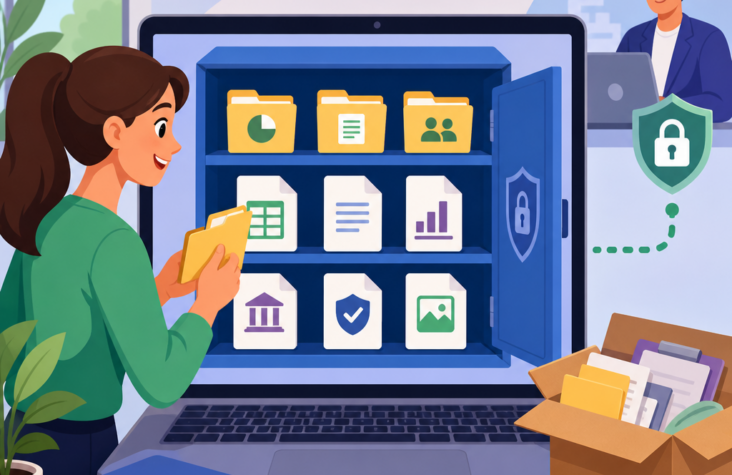
In M&A, a virtual data room is a secure digital repository where a seller stores the financial, legal, operational, commercial, and technical documents a buyer needs to evaluate the business. Due diligence is the buyer’s deep review of what was presented during marketing and management conversations. Deal execution is everything that happens between signed interest and closing: diligence, drafting, negotiating, confirming assumptions, and resolving risk. For founders, this matters because a poorly prepared data room creates delays, weakens trust, invites retrading, and can kill a deal that otherwise should close.
I have watched diligence processes go sideways for one simple reason: management assumed they could “pull documents together later.” Later is when buyers start asking harder questions, lawyers start marking up agreements, and small inconsistencies become big credibility problems. A clean virtual data room does more than store files. It tells buyers that the company is disciplined, transparent, and ready for transition. It also helps management answer requests quickly without disrupting the day-to-day operation of the business.
This article is the hub for due diligence and deal execution resources under Tools, Checklists, and Resources. It explains what belongs in a virtual data room before buyer access begins, how to structure it, and which categories of documents should be complete before diligence starts. It also points founders toward the broader discipline behind exit readiness: clean financials, documented operations, clear ownership, and fast response capability. Buyers do not just buy growth. They buy confidence in that growth.
Why the Virtual Data Room Matters Before Diligence Starts
A data room should be substantially built before any buyer receives access because speed and consistency affect valuation. The first buyer questions are rarely the dangerous ones. The dangerous problems appear when responses are late, documents conflict, signatures are missing, or financial schedules do not tie to the quality of earnings narrative. A buyer who senses disorder will widen diligence, involve more advisors, and start negotiating from a risk discount rather than a growth premium.
Well-prepared sellers use the data room to support the deal story already presented in teasers, confidential information memorandums, management presentations, and conversations. Numbers must match. Definitions must match. Customer concentration, add-backs, recurring revenue, churn, pipeline, and forecasts must all be reconcilable. If management says revenue is diversified and the data room shows one customer at 28 percent of sales, the issue is no longer concentration alone. It is trust.
Preparation also protects management time. During active diligence, founders are already balancing buyer calls, internal operations, employee confidentiality, and legal workstreams. If every request requires a last-minute hunt through inboxes and file cabinets, the process becomes chaotic. A strong data room turns reactive scrambling into controlled execution.
How to Structure the Data Room for Buyer Confidence
The best virtual data rooms are simple, logical, and complete. They are not dumping grounds. Folder names should follow the way buyers and advisors actually review a company: corporate, financial, tax, commercial, human resources, legal, operations, technology, and transaction-specific materials. File names should be clear, dated, and version controlled. If a document is superseded, the outdated version should be removed or marked clearly.
Access discipline matters too. Use tiered permissions when appropriate. Highly sensitive items such as executive compensation details, customer names in early-stage bidding, or source code access may need phased release. Watermarking, download restrictions, and user-level access logs should be enabled where relevant. A buyer should never wonder whether the seller knows who has seen what.
Include an index and maintain a request tracker. One of the most useful practices is mapping each major diligence topic to a folder and subfolder structure before documents are uploaded. That approach reduces duplicate requests and helps the seller identify missing materials early.
Core Document Categories Every Data Room Should Include
Before buyer access begins, the seller should have the following major categories prepared.
| Category | What Buyers Expect | Why It Matters |
|---|---|---|
| Corporate Records | Formation docs, bylaws, board consents, cap table | Confirms legal ownership and authority to sell |
| Financial Information | Historical statements, monthly reporting, forecasts, add-back support | Validates earnings quality and valuation assumptions |
| Tax Materials | Federal, state, local filings and correspondence | Reveals liabilities and compliance risk |
| Commercial Data | Customer lists, contracts, retention metrics, pipeline | Tests revenue durability and growth claims |
| Human Resources | Org chart, agreements, compensation, benefits | Shows team stability and transferability |
| Legal & Compliance | Material contracts, disputes, policies, permits | Identifies contingencies and deal friction |
| Operations | SOPs, vendor terms, facilities, insurance | Demonstrates the business can run consistently |
| Technology & IP | IP ownership, software stack, licenses, security | Critical for defensibility and integration planning |
Corporate, Ownership, and Governance Materials
Start with legal existence and ownership. Buyers need the articles of incorporation or organization, bylaws or operating agreement, amendments, shareholder agreements, voting agreements, and all board and shareholder consents relevant to major decisions. Include the current capitalization table, option schedules, warrant details, convertible instruments, and any rights of first refusal or transfer restrictions.
If there are subsidiaries, include their governing documents and intercompany agreements. If ownership has changed over time, organize historical records so counsel can trace the chain clearly. Missing signatures, unsigned option grants, or contradictory cap tables can create disproportionate legal work late in the process. For founder-led businesses that have never been through institutional review, this is often one of the first pressure points.
Financial Statements, KPIs, and Forecast Support
The financial section should include at least three years of historical profit and loss statements, balance sheets, and cash flow statements, plus current year monthly results and trailing twelve-month performance. Reconcile management statements to tax returns and, if applicable, reviewed or audited statements. If the deal is being marketed on adjusted EBITDA, provide a schedule of add-backs with clear support for each item. Unsupported adjustments are one of the fastest ways to invite valuation pressure.
Buyers also expect monthly KPI reporting. Depending on the business, that may include recurring revenue, churn, customer acquisition cost, gross margin by line, backlog, bookings, utilization, cohort performance, average order value, or unit economics. Forecasts should not be aspirational fiction. They should tie to historical patterns, pipeline assumptions, pricing logic, and operating plans. A forecast that cannot be explained in five minutes will not survive diligence.
Tax, Compliance, and Government Filings
Include federal, state, and local tax returns, sales and use tax filings where relevant, payroll tax records, nexus analyses if applicable, and any correspondence with taxing authorities. If there are payment plans, audits, unresolved notices, or exposure in specific jurisdictions, disclose them in an organized way with status notes. Buyers do not expect perfection. They expect visibility.
Regulatory materials belong here as well when relevant to the industry: permits, licenses, environmental reports, industry certifications, privacy compliance materials, and policy documents. If the company operates across states or countries, make sure cross-jurisdiction obligations are easy to follow. The more fragmented the regulatory footprint, the more important structure becomes.
Customer, Revenue, and Commercial Documentation
This is where the sale narrative either strengthens or weakens. Include a customer list with revenue by customer for at least three years, concentration analysis, churn or retention data, top customer contracts, pricing schedules, renewal terms, backlog if relevant, and any side letters or unusual concessions. If confidentiality requires redaction early, the unredacted versions should still be ready for later-stage access.
Add sales pipeline reports, booked-but-not-billed work, major proposal statuses, and channel partnership agreements. If recurring revenue is part of the value story, show the actual mechanics: contract length, cancellation rights, renewal behavior, historical retention. If growth is driven by a few channels, document that. If one large account is expected to decline, note that internally before a buyer discovers it alone.
Human Resources, Compensation, and Organizational Depth
Buyers want to know whether the company can perform after closing. That requires understanding the team. Include an organizational chart, employee census, compensation summaries, offer letters or employment agreements, confidentiality and invention assignment agreements, bonus plans, commission structures, equity plans, and retention risks. Key executive agreements should be easy to locate.
Benefits plans, handbook policies, independent contractor arrangements, immigration documentation where relevant, and any ongoing HR disputes should also be included. A founder-dependent business already creates concern. Weak documentation around key personnel magnifies it. If the company has strong second-layer leadership, the data room should make that visible.
Legal Matters, Material Contracts, and Risk Areas
Material contracts deserve their own carefully labeled sections. Include leases, loan agreements, security documents, guarantees, major vendor contracts, customer agreements, software licenses, reseller agreements, distribution contracts, and any agreements with change-of-control provisions. Buyers care deeply about provisions that can trigger consent requirements or termination rights when ownership changes.
Also include litigation summaries, settlement agreements, claims history, demand letters, and insurance coverage. If there are unresolved issues, add management notes so the context is available immediately. Silence forces buyers to imagine the worst-case scenario, and worst-case scenarios reduce price.
Operations, Technology, and Intellectual Property
Operational maturity supports value. Upload standard operating procedures, workflow maps, quality control documentation, vendor scorecards, procurement practices, logistics arrangements, and facility information where relevant. If the company runs on a few key systems, explain what they are and how they are managed.
For technology and IP, include trademark and patent filings, domain ownership, copyright registrations, software architecture overviews, code repository ownership, third-party licenses, open-source policies, cybersecurity policies, penetration testing or security reports, privacy policies, and disaster recovery plans. If contractors developed part of the product, their IP assignment agreements must be available. A buyer will not assume ownership where the paper trail is weak.
What Should Be Ready Before Access Is Granted
Before any buyer receives credentials, the room should be materially complete in the core areas above, not partially assembled. That does not mean every low-priority file must already be uploaded. It means the room must support a serious first pass by a buyer and its advisors without exposing obvious disorganization. Corporate records, historical financials, major contracts, tax returns, leadership documents, and commercial schedules should all be ready.
There should also be a response protocol. Decide who owns financial questions, who handles legal requests, who approves additional uploads, and how management notes will be shared. One of the most effective approaches is to maintain a diligence Q&A log with request date, owner, response date, and status. That keeps everyone aligned and prevents contradictory answers.
How This Hub Connects to Broader Due Diligence and Deal Execution Resources
This page is the hub for due diligence and deal execution resources because the data room sits at the center of every serious transaction. Around it are the other tools founders need: diligence request lists, quality of earnings prep, legal cleanup checklists, customer concentration analysis, working capital planning, management presentation prep, and LOI review guidance. If you are building toward a sale, this is not a one-document exercise. It is a discipline.
Founders who want to go deeper should also review broader exit planning frameworks and M&A execution guidance through the Legacy Advisors resource library and podcast content. Many of the strategic ideas behind readiness, transferability, valuation, and diligence preparation are also covered in The Entrepreneur’s Exit Playbook, especially for owners who know they want optionality but are not yet committed to a sale process.
A strong virtual data room does not guarantee a great exit, but a weak one almost guarantees unnecessary friction. Build it before buyer access begins, structure it the way professionals review deals, and use it to prove that your business is organized, credible, and transferable. That is what buyers pay for. If you are serious about due diligence and deal execution resources, start here, then keep building every supporting system around it. Preparation is leverage, and leverage is value.
Frequently Asked Questions
What documents should be in a virtual data room before buyer access begins?
Before buyer access starts, a virtual data room should contain the core materials a serious buyer will expect to review during diligence, organized in a way that lets them verify the business quickly and confidently. At a minimum, that usually includes corporate formation and governance documents, capitalization records, historical financial statements, monthly performance reporting, tax filings, material customer and vendor contracts, employee and compensation information, intellectual property records, litigation or compliance files, insurance policies, operational documentation, and any technical or product materials that are relevant to how the company actually runs. If the business has debt, leases, regulatory licenses, data privacy obligations, cybersecurity policies, or board materials that influence risk or performance, those should also be prepared in advance.
The real objective is not just completeness, but readiness. Buyers want to see that the company’s records support the story told in management meetings and marketing materials. If revenue concentration was discussed, the key contracts behind that revenue should already be there. If growth, margins, retention, or product differentiation are central to the sale narrative, the supporting reports and documentation should be easy to locate. A strong data room gives buyers the ability to move from high-level claims to underlying proof without friction. That reduces back-and-forth, shortens diligence timelines, and helps preserve seller leverage because the process feels controlled rather than reactive.
How organized should a virtual data room be before buyers are invited in?
It should be highly organized before any buyer receives access. A virtual data room is not just a storage folder; it is the control center of a live transaction. If documents are uploaded piecemeal, mislabeled, duplicated, or buried in inconsistent folders, buyers interpret that as a warning sign. Even when the underlying business is strong, poor organization creates doubt about financial discipline, legal hygiene, and management preparedness. That can slow diligence, increase buyer skepticism, and open the door to price chips or expanded indemnity demands later in the process.
Best practice is to structure the room by major diligence category, using clear folder names and a logical document hierarchy. Files should have consistent naming conventions, be current, and be reviewed for completeness before access begins. It is also wise to identify missing items in advance, either by locating them, remediating the issue, or preparing a clean explanation for why something is unavailable. A well-organized room allows buyers to navigate efficiently, keeps the process moving on the seller’s timetable, and signals that management is serious, credible, and prepared for scrutiny. In competitive sale processes, that level of discipline can materially improve momentum and confidence.
Why is it risky to open the data room before it is fully prepared?
Opening a virtual data room too early often weakens the seller’s position faster than founders expect. Once buyers begin diligence, they start forming judgments not only about the business itself, but about the quality of the process. If basic records are missing, if important schedules do not reconcile, or if key agreements are still being “pulled together,” buyers may conclude that other issues are also undiscovered or unmanaged. That uncertainty tends to produce more questions, broader diligence requests, slower internal approvals on the buyer side, and increased pressure for contractual protections or price adjustments.
There is also a practical risk. An unprepared room creates an endless reactive cycle: management spends time answering avoidable questions, intermediaries chase documents under deadline pressure, and new uploads arrive without context. That chaos can distract leadership from running the business during a critical period and can create inconsistent responses across buyers if more than one party is involved. Preparing the room in advance allows the seller to control the flow of information, anticipate likely diligence concerns, and address vulnerabilities before they become negotiation problems. In other words, timing matters. Buyer access should begin when the room can support a coherent, defensible diligence story from day one.
How do founders decide what belongs in the room immediately versus what can be shared later?
Founders should think about disclosure in phases, but the room still needs to be substantially complete before buyer access begins. The first phase should cover the materials required to validate the company’s core story: legal existence and ownership, historical financial performance, tax status, major contracts, workforce information, operational infrastructure, and any issues that could materially affect value or closing certainty. These are the items buyers need early to determine whether the opportunity matches what was presented. Holding back ordinary diligence materials usually does not create leverage; it typically creates suspicion.
That said, some information may be staged based on sensitivity and buyer status. For example, highly confidential competitive details, customer-identifying information, source code access, or information tied to a later-stage confirmatory review may be reserved for a narrower set of parties or released after a buyer reaches a more advanced stage. The key is to make those decisions intentionally, not because the materials were not ready. Sellers should balance confidentiality with credibility, using permissions, redactions, and phased access where appropriate. A disciplined approach ensures that buyers receive enough information to stay engaged and bid aggressively, while the company still protects its most sensitive assets until the process justifies deeper exposure.
What are the most common virtual data room mistakes that hurt deal execution?
The most common mistakes are missing documents, inconsistent financial information, poor folder structure, outdated files, and a failure to identify issues before buyers do. Another frequent problem is loading large volumes of documents without context, which forces buyers to spend time figuring out what matters and why. That can lead to duplicated questions, slower diligence cycles, and unnecessary concern about internal controls. Founders also sometimes underestimate how closely buyers compare the data room to the claims made in the teaser, CIM, management presentation, and executive conversations. Any disconnect between the narrative and the documentation can erode trust quickly.
Other damaging mistakes include weak version control, overbroad access permissions, inadequate redaction of sensitive information, and delaying uploads of known problem areas such as contract exceptions, tax exposure, cap table complexity, IP assignments, or compliance gaps. Those issues rarely improve with delay. In fact, when they appear late, buyers often assume they were intentionally withheld. The strongest approach is to pressure-test the room before launch, reconcile numbers across reports, ensure legal and financial materials align, and prepare concise explanations for any exceptions or historical irregularities. Good deal execution depends on reducing surprise, preserving momentum, and maintaining buyer confidence. A clean, complete, thoughtfully prepared virtual data room is one of the most effective ways to do all three.