

What PE Case Studies Reveal About Good and Bad Exit Outcomes
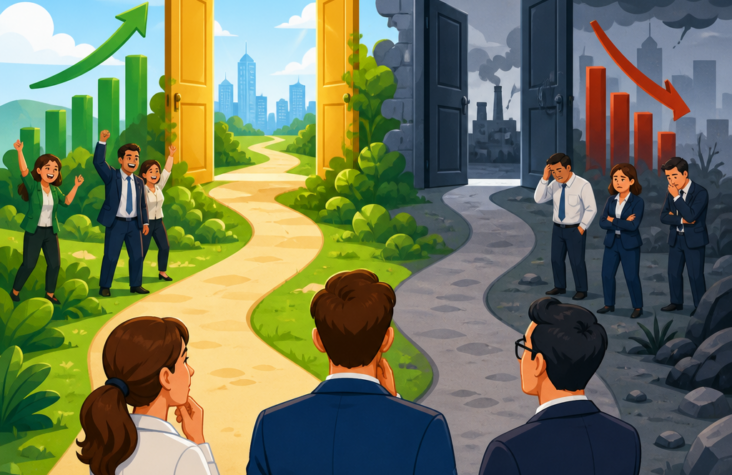
Private equity case studies reveal a simple truth: good and bad exit outcomes are rarely decided at the closing table. They are usually determined years earlier by the quality of the asset, the discipline of management, the capital structure, and the realism of the growth plan. For founders, executives, and investors, that matters because private equity is no longer a niche corner of finance. It is one of the dominant forces shaping acquisitions, recapitalizations, roll-ups, and founder liquidity events across the middle market.
To understand why some exits create exceptional returns while others disappoint, it helps to define a few core terms. Private equity refers to capital invested in privately held companies, typically through buyouts, growth investments, or recapitalizations. An exit is the event where that investment is monetized, usually through a sale to a strategic buyer, a sale to another sponsor, a recapitalization, or an initial public offering. A good exit outcome does not just mean a high headline valuation. It means strong net proceeds after debt, taxes, transaction fees, working capital adjustments, and earn-out risk. A bad exit outcome may still generate cash, but often leaves value on the table because of poor timing, weak preparation, concentrated risk, or unrealistic underwriting.
In my work with founders preparing for sale, I have seen the same pattern repeat: owners focus on revenue, while buyers focus on durability, margin quality, and transferability. Private equity case studies make those priorities unmistakably clear. The deals that win tend to feature recurring revenue, professionalized reporting, scalable systems, and management teams that can operate without constant founder intervention. The deals that struggle usually show the opposite. This article serves as a hub for advanced strategies and case studies in private equity and capital markets, bringing together the key lessons leaders need before they engage with sponsors, lenders, or potential acquirers.
What Strong Private Equity Exits Consistently Have in Common
Good private equity exits usually start with a business that became more investable during the hold period, not merely bigger. That distinction matters. A company can double revenue and still underperform at exit if the growth came from low-margin work, customer concentration, or operational sprawl. The best case studies show improvement in several dimensions at once: EBITDA growth, margin expansion, leadership depth, reporting quality, and strategic positioning.
A classic pattern appears in sponsor-backed business services and software deals. A fund acquires a platform company with solid margins, then improves pricing discipline, upgrades reporting, and adds tuck-in acquisitions that expand geography or service breadth. By the time the company returns to market, buyers are not only underwriting historical performance. They are buying a cleaner, more scalable platform with lower perceived risk. That lower risk often drives the real multiple expansion.
The most attractive exits also benefit from a credible management bench. Buyers pay more when they believe the next phase of growth does not depend on one founder answering every client call, approving every hire, and driving every sale. In practice, this means a strong operator, a finance leader who can support diligence, and enough process maturity that the business feels transferable. In many successful exits, the hold period looks like a transformation from founder-led improvisation to institutionally credible execution.
What Bad Exit Outcomes Usually Signal Before the Sale Process Starts
Bad exits rarely come out of nowhere. The warning signs are visible long before the company goes to market. The first is weak earnings quality. If EBITDA depends on aggressive add-backs, underinvestment in talent, or temporary revenue spikes, buyers will challenge the story. The second is customer concentration. When one or two customers represent an outsize share of revenue, buyers apply discounts because future cash flow is less certain. The third is founder dependence, which can force a seller into a longer rollover or earn-out than expected.
Another common issue is capital structure mismatch. Some companies are sold carrying too much debt, which narrows buyer interest and reduces flexibility during diligence. Others were bought at peak multiples and then failed to grow into the entry valuation. In those cases, even a competent operating performance can lead to a disappointing exit because the math was flawed at the start. Private equity does not escape arithmetic. If a sponsor overpays and leverage is expensive, there is less room for error later.
I have also seen poor outcomes driven by what looks like success on paper. A company may report rapid growth, but if that growth requires relentless cash burn, constant founder heroics, or deeply discounted pricing, the market notices. Sophisticated buyers today are faster and more forensic than many sellers expect. They are not buying hype. They are buying repeatable economics.
How Entry Price and Leverage Shape Exit Results
One of the clearest lessons from private equity case studies is that exit quality often begins with entry discipline. A fund that buys a company at a sensible multiple with manageable leverage has multiple paths to a good outcome. A fund that stretches on price and debt has to execute almost perfectly. That is why credit conditions and rate environments matter so much in capital markets.
When interest rates were low, many sponsors could rely on cheap debt and strong buyer demand to support high valuations. As rates rose, deals needed more genuine operational value creation. That changed what good and bad outcomes looked like. In a tighter market, businesses with recurring revenue, margin resilience, and low churn still commanded strong interest. Businesses with cyclical demand, weak reporting, or thin margins saw greater pressure on valuation.
Leverage can magnify returns, but it can also destroy flexibility. In positive case studies, debt is used as a tool, not a crutch. Cash flow comfortably services obligations, covenants are realistic, and management has room to invest in growth. In negative case studies, the debt load limits hiring, technology upgrades, or strategic acquisitions. When performance softens, the company becomes reactive. At exit, the enterprise value may look acceptable, but equity proceeds disappoint because too much value flows to debt repayment.
| Case Pattern | Good Exit Outcome | Bad Exit Outcome |
|---|---|---|
| Entry valuation | Bought at disciplined multiple with room for upside | Bought at peak pricing with little margin for error |
| Leverage profile | Debt supports growth and remains serviceable | Debt constrains decisions and compresses equity value |
| Revenue quality | Recurring, diversified, contract-backed | Project-based, concentrated, volatile |
| Management strength | Independent leadership team in place | Founder dependence remains high |
| Operational maturity | Documented systems and reliable reporting | Inconsistent KPIs and weak controls |
| Exit environment | Multiple buyer types competing | Limited buyer pool and weak market timing |
What Roll-Up Case Studies Teach About Integration Risk
Roll-up strategies have produced some of the most impressive private equity wins, but they also generate some of the most painful misses. The strategy seems straightforward: acquire a platform, add smaller businesses, realize synergies, and exit at a larger scale with a better multiple. In practice, the outcome depends on integration discipline.
Good roll-up exits usually share three features. First, they buy within a focused thesis, not across random adjacency. Second, they have a clear integration playbook covering finance, systems, pricing, reporting, and talent retention. Third, they preserve what made the acquired businesses attractive while eliminating unnecessary redundancy. In sectors like HVAC, healthcare services, and niche B2B services, sponsors have done this well by standardizing back office functions while keeping local market strengths intact.
Bad roll-ups often fail because management underestimates complexity. Different ERP systems, inconsistent pricing, incompatible cultures, and poor post-close communication create friction that drains the supposed synergies. Revenue suffers, key people leave, and integration consumes leadership attention. By the time the sponsor seeks an exit, the platform is bigger but less coherent. Buyers sense that and discount accordingly.
This is especially relevant for founders considering joining a PE-backed platform. The right sponsor can accelerate value. The wrong one can force awkward integration, erode culture, and reduce the very differentiation that attracted buyers in the first place.
Why Sector Selection Matters in Private Equity Case Studies
Not all sectors produce the same kind of exits. Private equity case studies consistently show that industry structure influences buyer demand, financing availability, and valuation resilience. Software, healthcare, outsourced business services, and specialized industrial niches often perform well because they offer recurring demand, fragmentation, and opportunities for operational improvement. Sectors tied closely to discretionary spending, commodity pricing, or regulatory uncertainty can still produce wins, but they tend to require sharper timing and stronger downside management.
Consider the difference between vertical SaaS and a generalist consumer brand. Vertical SaaS often benefits from sticky workflows, contractual revenue, and expansion potential through upsells. A consumer brand may have strong upside, but it also faces platform dependence, higher customer acquisition volatility, and more unpredictable margin pressure. Buyers know this, so the same top-line growth can command very different outcomes.
For founders, the lesson is practical. You cannot change your sector overnight, but you can shape how your business is positioned within it. If your market is volatile, build stronger contracts. If your space is fragmented, show a clear consolidation thesis. If your margins are pressured, prove pricing power or efficiency gains. Case studies reward context, not just size.
How Management Quality Changes the Exit Multiple
In private equity, management quality is not a soft factor. It is a valuation factor. Buyers pay more for teams they trust to deliver the next chapter. They discount heavily when they believe growth depends on one charismatic founder or one salesperson with all the relationships.
The best exits typically feature management that can speak confidently to financial trends, hiring plans, sales pipeline, operational KPIs, and strategic priorities. During diligence, this matters enormously. A disciplined CFO or controller can shorten diligence cycles and reduce buyer anxiety. A strong operations leader can explain how margin improvements are sustainable. A clear sales leader can show why growth is repeatable rather than accidental.
By contrast, poor exits often reveal gaps during management presentations. Buyers ask basic questions about gross margin trends, churn, or working capital, and the answers are vague. Forecasts are optimistic but unsupported. The founder dominates every conversation. At that point, valuation pressure is almost inevitable. A buyer may still proceed, but they will protect themselves with structure: larger rollover requirements, stronger indemnities, or contingent payments.
Advanced Exit Strategies PE Case Studies Highlight
The most sophisticated private equity exits are not always full sales. Some of the strongest outcomes come from partial liquidity, continuation vehicles, dividend recaps, or minority recapitalizations that let founders and sponsors take chips off the table while preserving future upside. These structures show up repeatedly in advanced case studies because they solve different problems at different stages.
A dividend recap can reward investors and founders after debt has been refinanced on better terms, but it only works when cash flow is durable. A minority recap can provide liquidity without surrendering full control, often attractive to founders who still want another growth chapter. Sponsor-to-sponsor sales can be excellent when the next buyer sees a larger platform opportunity than the first one could execute alone. Even IPOs, though less common in the middle market, still matter in sectors where public market appetite supports them.
The lesson is that exit strategy should be designed early. Founders who think only in terms of “sell or don’t sell” miss a wider set of options. Private equity case studies reveal that the best outcomes often go to owners who build optionality long before they need it.
What This Hub Means for Founders and Executives
As a hub for advanced strategies and case studies in private equity and capital markets, this page should guide how you read every related article that follows. The recurring themes are clear. Good exit outcomes come from disciplined entry valuation, resilient cash flow, diversified revenue, documented systems, and management depth. Bad outcomes usually stem from overreliance on founders, fragile margins, excess leverage, poor integration, or selling before the business is truly transferable.
If you are a founder, the takeaway is not that private equity is good or bad. It is that private equity is highly rational. Sponsors and buyers reward preparedness, clarity, and risk reduction. If you are an executive, your role in creating a strong exit is larger than you may think. Finance, operations, sales, and customer retention all shape how a buyer prices risk. If you are an investor, these case study patterns help you identify where real value creation is happening versus where growth is cosmetic.
The simplest way to use this hub is to ask one question: if a buyer looked closely at my company today, what would they love and what would they discount? Answering that honestly is the beginning of a better exit strategy. Then go deeper into each related article, assess your readiness, and start building the kind of business private equity case studies consistently reward. The best time to prepare was earlier. The next best time is now.
Frequently Asked Questions
1. What do private equity case studies usually show about the real drivers of a good exit outcome?
Private equity case studies consistently show that strong exits are not created at the moment of sale. They are built over several years through disciplined execution, smart capital allocation, and a realistic plan for value creation. In most successful examples, the asset itself has durable qualities from the beginning, such as recurring revenue, healthy margins, pricing power, strong customer retention, operational resilience, and a market position that can be clearly explained to buyers. By the time the company reaches the exit process, the most attractive features are already visible in the financials, the leadership team, and the company’s strategic narrative.
These case studies also highlight the importance of management discipline. Companies that exit well usually have leaders who understand cash flow, track key performance indicators closely, and make decisions based on operational reality rather than optimism. Buyers reward businesses that can demonstrate a repeatable growth engine, clean reporting, and an ability to perform through changing market conditions. In contrast, weak exits often trace back to overpromised projections, poorly integrated acquisitions, customer concentration, margin compression, or leverage that looked manageable during good times but became restrictive when growth slowed.
Another repeated lesson is that valuation at exit is heavily influenced by the credibility of the story. Buyers do not just pay for historical performance; they pay for confidence in future performance. Case studies of good exits often involve a company that can show not only past growth, but also why that growth is sustainable. That means the business is not dependent on one customer, one executive, one acquisition strategy, or one unusually favorable market cycle. The strongest outcomes usually come from preparation years in advance, not tactics used in the final weeks of a transaction.
2. Why is the quality of the asset so important in determining whether an exit will be successful or disappointing?
Asset quality is central because private equity buyers, lenders, and strategic acquirers are ultimately trying to assess durability. A high-quality asset is one that can perform predictably, scale efficiently, and maintain value even when conditions become less favorable. Case studies repeatedly show that businesses with recurring or highly visible revenue, strong gross margins, defensible differentiation, diversified customers, and low capital intensity tend to produce better exit outcomes because they are easier to underwrite and easier to believe in. Buyers are generally willing to pay more when they see a business that can sustain cash flow without heroic assumptions.
By contrast, lower-quality assets often depend on fragile conditions that eventually become obvious during diligence. This can include revenues tied to a small number of customers, aggressive revenue recognition, weak middle management, underinvestment in systems, or a business model that only works in unusually favorable economic conditions. In many disappointing exits, the problem is not that the company failed completely. It is that buyers recognized hidden fragility and discounted the valuation accordingly. In some cases, buyers walk away entirely when they conclude that earnings quality, customer retention, or operational controls are not as strong as initially presented.
Case studies also show that asset quality affects strategic flexibility throughout the hold period, not just at exit. Better assets can usually support investment in growth, attract stronger executive talent, access more favorable financing, and withstand short-term disruptions. Poorer assets tend to consume management attention, require repeated fixes, and leave less room for error. That is why sophisticated investors spend so much time evaluating the fundamentals early. A mediocre asset can sometimes be improved, but a weak foundation makes a premium exit much harder to achieve.
3. How does capital structure influence good and bad private equity exit outcomes?
Capital structure plays a major role because it determines how much flexibility a company has during the holding period and how much pressure exists to achieve a specific type of outcome. In the best case studies, leverage is used thoughtfully. Debt enhances returns, but it does not overwhelm the business. The company retains enough liquidity and covenant headroom to invest in operations, support acquisitions carefully, and absorb temporary setbacks without creating distress. This balance gives management the freedom to make long-term decisions that improve enterprise value rather than simply reacting to near-term financing constraints.
In weaker case studies, the capital structure often becomes the hidden reason an exit disappoints. Too much debt can limit hiring, technology investment, expansion initiatives, and pricing flexibility. It can also create urgency around timing, forcing an exit during a mediocre market window because the owners or lenders cannot afford to wait. Even if the underlying business is decent, excessive leverage can reduce strategic options and shrink buyer interest, especially if acquirers believe they will inherit risk, deferred investment needs, or unstable cash generation.
Case studies further reveal that capital structure matters psychologically as well as financially. A heavily levered company often operates under constant pressure to hit short-term targets, which can encourage cosmetic decisions such as cutting necessary spending, delaying maintenance, or pushing unrealistic forecasts. Those choices may help temporarily, but they often show up later in diligence and hurt credibility. A sensible capital structure, on the other hand, supports cleaner execution and a more convincing exit narrative. In simple terms, debt can magnify a good business, but it can just as easily expose a fragile one.
4. What role does management execution play in separating strong exits from weak ones?
Management execution is one of the clearest dividing lines between favorable and unfavorable exit outcomes. Private equity case studies often show that a good company can still produce a mediocre result if management fails to translate opportunity into measurable performance. Strong execution means more than hitting a revenue number. It includes building a reliable operating cadence, developing a capable leadership bench, integrating acquisitions effectively, maintaining pricing discipline, and producing reporting that stands up under rigorous due diligence. Buyers pay for confidence, and confidence comes from evidence that the team can run the business without chaos or dependence on one person.
When management is strong, the business tends to become more institutional over time. Financial controls improve, forecasting becomes more accurate, customer churn is understood and managed, and operational risks are surfaced early rather than hidden. This creates a smoother sale process because buyers encounter fewer surprises. In many of the best exit case studies, management teams are able to explain not only what happened, but why it happened and what will happen next. That level of command increases buyer trust and often supports stronger competition in the process.
On the negative side, weak execution usually leaves fingerprints everywhere. Missed integration targets, unexplained margin swings, unreliable forecasts, high turnover, poor communication between finance and operations, and inconsistent sales performance all make buyers cautious. Even when headline growth looks attractive, a sloppy operating model can reduce value because acquirers anticipate future cleanup costs and execution risk. The lesson from case studies is clear: the market rewards businesses that look controlled, scalable, and managerially mature. It discounts businesses that still look founder-dependent, improvisational, or internally fragmented.
5. What should founders, executives, and investors learn from PE case studies before planning an exit?
The biggest lesson is to think about the exit much earlier than most people expect. Case studies show that outcomes are shaped years before the transaction process begins. Founders, executives, and investors should focus on building a business that can withstand scrutiny, not just one that looks good in a teaser or management presentation. That means investing early in financial controls, building a durable management team, reducing customer concentration, documenting key processes, and making sure growth assumptions are anchored in evidence rather than ambition. A business that is prepared for diligence well in advance typically has more options, stronger negotiating leverage, and fewer valuation surprises.
Another key lesson is to be realistic about what buyers value. Many internal teams assume that top-line growth alone will drive a premium exit, but private equity case studies repeatedly show that buyers care just as much about earnings quality, cash conversion, market defensibility, and execution credibility. A rapid growth story can still disappoint if margins are unstable, working capital is stretched, or results depend on unsustainable sales tactics. The most successful exit planning starts with honest self-assessment: what risks will a buyer identify, what objections will appear in diligence, and what evidence exists to answer them convincingly?
Finally, these case studies remind all stakeholders that timing matters, but preparation matters more. Market conditions can help or hurt valuation at the margin, yet weak fundamentals are difficult to hide in any environment. Conversely, a strong business with disciplined management and a coherent growth plan can still attract quality buyers even in a tougher market. For founders considering liquidity, executives preparing for a sale process, or investors underwriting future returns, the practical takeaway is straightforward: build the company you would want to buy yourself. That mindset tends to produce better operations during the hold period and better outcomes at exit.