


What PE Buyers Mean by Platform, Add-On, and Buy-and-Build
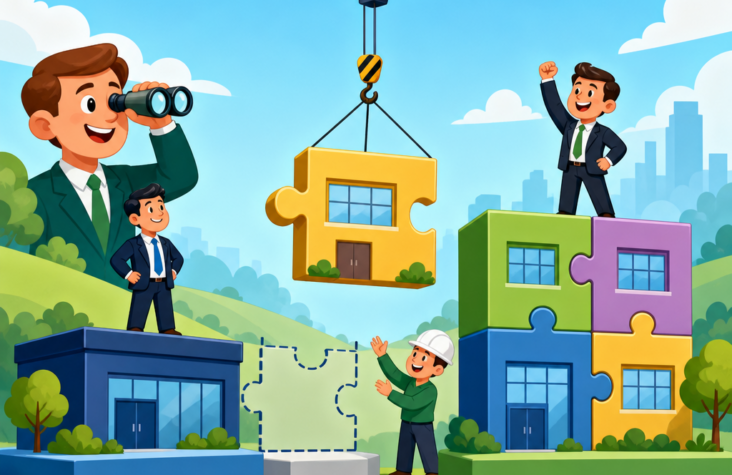
Private equity shapes a large share of middle-market mergers and acquisitions, yet many founders still hear terms like platform, add-on, and buy-and-build without fully understanding what buyers mean. In practical terms, private equity refers to investment firms that raise capital from institutions and wealthy investors, buy private companies, improve them, and eventually sell them for a return. A platform company is the initial business a private equity firm acquires as the foundation for a larger strategy. An add-on, sometimes called a tuck-in, is a later acquisition folded into that platform to expand scale, geography, customers, or capabilities. Buy-and-build is the overall playbook: acquire a strong core company, then grow it through additional acquisitions and operational improvements. I have sat across from founders who assumed these were just finance buzzwords. They are not. They determine valuation, timing, control, deal structure, and what your life looks like after closing. For entrepreneurs, business owners, and investors, understanding private equity is not optional anymore. It is part of understanding how modern deals get done, why one buyer pays a higher multiple than another, and why some companies are pursued aggressively while others are passed over. If you are building a company in manufacturing, business services, healthcare, software, distribution, consumer products, or a niche industrial vertical, this hub will help you interpret how private equity buyers think and how to prepare for their interest.
Understanding Private Equity and Why It Matters to Founders
Private equity firms pool money from limited partners such as pension funds, endowments, family offices, and insurance companies. The private equity firm acts as the general partner and deploys that capital into acquisitions. In the lower middle market and middle market, those acquisitions are often profitable privately held companies with recurring customers, defensible niches, and room for operational improvement. The firm typically holds investments for three to seven years, although timelines vary by strategy and market conditions. During that period, the goal is usually straightforward: grow earnings, improve systems, complete acquisitions, and sell at a higher valuation multiple than the one paid at entry.
For a founder, that matters because private equity is often a different buyer than a strategic acquirer. A strategic buyer may want your company because it fits an existing operation, eliminates a competitor, or adds intellectual property. A private equity buyer usually wants a return engine. That means it studies EBITDA, customer concentration, management depth, recurring revenue, working capital needs, and the ability to support leverage. It also means the same company can receive very different offers depending on whether the buyer sees it as a platform, an add-on, or a future roll-up candidate. Founders who understand private equity negotiate from a stronger position because they know what drives value on the other side of the table.
What a Platform Company Really Means
A platform company is the first meaningful acquisition in a private equity firm’s strategy for a specific niche. Think of it as the anchor asset. It is not simply the largest company in a space. It is the company the investor believes can support leadership, financing, reporting, compliance, and future acquisitions. In my experience, the best platform candidates usually have several traits at once: strong management, reliable financial reporting, healthy margins, a repeatable sales process, and a market position broad enough to absorb smaller businesses.
For example, a private equity firm might buy a regional HVAC services business with $8 million of EBITDA, strong service contracts, and a management team that can stay post-close. That company becomes the platform. The PE firm may then invest in technology, recruit additional operators, and centralize functions like accounting or procurement. From there, it looks for smaller HVAC companies in nearby geographies to fold into the platform. The platform matters because it sets the valuation benchmark, culture, and integration capacity for everything that follows.
Being labeled a platform can benefit a seller. Platform deals often command stronger valuations than comparable add-ons because the buyer is not just purchasing cash flow; it is purchasing the base from which an entire investment thesis will grow. But the standard is higher. If you are being evaluated as a platform, buyers will pressure test whether the business can run without founder heroics, whether the management bench is deep enough, and whether financial controls are sophisticated enough for debt lenders and future acquisitions.
What an Add-On Acquisition Means
An add-on acquisition is a business purchased after the platform is in place. Add-ons are usually smaller than the platform and are acquired because they strengthen the larger whole. They may expand geography, add customers, deepen technical capability, improve talent density, or create purchasing leverage. A good add-on does not need to be perfect as a standalone enterprise. It needs to make the platform more valuable.
Suppose a private equity-backed marketing services platform acquires a specialized SEO agency serving enterprise healthcare clients. On its own, that agency may be too small to attract broad buyer attention. As an add-on, however, it may be highly attractive because it gives the platform a new vertical, better margins, and cross-sell opportunities into an existing client base. The add-on may keep its brand for a period, or it may be fully integrated, depending on the buyer’s strategy.
Add-ons often trade at lower multiples than platforms because they rely on the platform’s infrastructure. That does not mean founders should accept weak terms automatically. In some cases, an add-on is so strategically useful that a buyer will stretch on price. I have seen that happen when a target brings a marquee customer list, a scarce technical capability, or a key geography that accelerates the whole buy-and-build plan. Still, founders should understand the default mindset: the buyer is usually underwriting synergies and expecting integration benefits.
What Buy-and-Build Means in Plain English
Buy-and-build is the strategy of acquiring one good company and then growing it by acquiring others around it. It is one of the most common private equity playbooks in fragmented industries. Fragmented markets are ideal because there are many subscale operators, often founder-led, with inconsistent systems and limited access to growth capital. Private equity sees an opportunity to assemble those smaller pieces into a larger business that deserves a premium multiple at exit.
The logic is simple. If a PE firm buys a platform at, for example, 7x EBITDA, then buys several add-ons at 4x to 6x EBITDA, and integrates them into a stronger enterprise, the combined business may later sell for 9x or 10x EBITDA. That spread between entry and exit multiples, combined with earnings growth, creates returns. Operational improvements amplify the result: better pricing, shared services, centralized finance, improved sales management, lower purchasing costs, and better talent recruitment.
This strategy has been used for decades in industries such as dental practices, veterinary clinics, managed IT services, HVAC, fire and life safety, healthcare staffing, industrial distribution, software, home services, and environmental services. It works best when the buyer can professionalize the business without breaking what made the local operators successful in the first place.
How PE Buyers Distinguish Platform vs Add-On Targets
Not every attractive company becomes a platform. Sometimes founders think size alone decides the issue, but buyers assess a wider set of factors. The table below shows the distinctions clearly.
| Factor | Platform Candidate | Add-On Candidate |
|---|---|---|
| Scale | Usually larger, with meaningful EBITDA and lender appeal | Usually smaller, often below platform lending thresholds |
| Management Team | Needs a strong team that can lead future growth | May rely more heavily on founder or local operators |
| Systems and Reporting | Expected to have stronger financial controls and data | Can be less mature if platform can absorb it |
| Strategic Role | Foundation for the investment thesis | Enhances the thesis through expansion or capability |
| Valuation | Often higher multiple | Often lower multiple unless uniquely strategic |
| Post-Close Integration | Sets integration model for future deals | Usually integrated into platform processes |
Why Founders Should Care About the Label
The platform versus add-on distinction affects almost every term in your deal. A platform seller may receive a richer valuation, have more influence over governance, and be asked to roll equity into the new parent company. A founder of an add-on may still be offered rollover equity, but the buyer’s expectations are often different. Integration can be faster, autonomy can shrink, and earn-outs may be tied more tightly to transition performance.
It also shapes the story the buyer tells lenders and investors. If your company is the platform, you are the story. If you are the add-on, you are supporting evidence. That distinction matters in negotiations because it tells you where leverage may exist. If a buyer needs your geography to complete a regional map or your service line to deepen margins, you may have more pricing power than a generic add-on. If not, the buyer may treat the opportunity like one of many available targets.
This is one reason founders benefit from understanding private equity before going to market. The more clearly you can position your company within a PE buyer’s thesis, the more effectively you can frame your value. In our advisory work, this often means explaining whether the business should be marketed as a standalone platform, a scarce add-on, or a company that needs another year or two of preparation before either path makes sense.
What PE Firms Look For in Each Type of Deal
For platform deals, buyers usually focus on management quality, reporting discipline, market size, and the ability to complete future acquisitions. They want evidence that the company can support debt, absorb additional businesses, and continue growing without depending entirely on the founder. For add-ons, they may tolerate more founder dependence or less mature systems if the strategic fit is compelling and integration is straightforward.
In both cases, recurring revenue, customer retention, pricing power, and margin quality matter. So do concentration risks. A company with one customer representing 35% of revenue may still sell, but the buyer will haircut value unless there is a strong explanation and a mitigation path. The same is true for weak middle management, outdated financial reporting, or legal issues around contracts and compliance.
Founders often ask whether growth or profitability matters more. The answer is both, but the balance depends on the sector. In software, growth may dominate the story. In industrial or business services, clean EBITDA and predictability can matter more. The private equity lens is always grounded in eventual exit value. Buyers are asking, directly or indirectly, what they can own this asset for today, how much they can improve earnings, and what multiple they can get when they sell.
How Deal Structure Changes in PE Transactions
Private equity deals often include terms that differ from simple all-cash strategic acquisitions. Equity rollover is common, especially in platform deals. That means the founder sells part of the company but reinvests a percentage into the new parent entity. The appeal is straightforward: take money off the table now and participate in the future upside when the PE firm exits. This is the “second bite of the apple” many founders hear about.
Earn-outs can also appear, though quality buyers generally prefer clear alignment rather than overly aggressive contingent structures. Employment agreements, non-competes, and retention arrangements for key managers are standard. If the buyer is using leverage, lenders may influence covenants and reporting expectations. Founders should not view these terms as automatically bad; they should view them as tools that need to be negotiated intelligently.
This is also where understanding private equity helps emotionally. PE firms are not usually buying your company to preserve it exactly as it is. They are buying it to improve, scale, and later sell it. That does not mean culture is irrelevant, but it does mean you should expect change. Founders who are clear-eyed about that dynamic make better decisions about whether the deal is right for them.
How to Prepare if You Want Private Equity Interest
If you want to attract private equity buyers, start by building a business that does not rely on heroics. Clean monthly financials matter. A credible management team matters. Documented processes matter. Recurring or repeatable revenue matters. Customer concentration, legal issues, and unclear ownership structures should be addressed before diligence, not during it.
You should also understand how your company would be perceived: platform, add-on, or not yet ready. That answer influences valuation expectations and buyer targeting. Many founders wait too long to think this through. A better approach is to prepare years in advance, because the best exits are built long before the LOI arrives. If you want a deeper roadmap, The Entrepreneur’s Exit Playbook lays out that preparation in detail: https://amzn.to/3NOnNVH.
Using This Hub to Learn Private Equity the Right Way
This article is the hub for understanding private equity inside the broader capital markets conversation. From here, founders should keep learning how PE firms value businesses, how leverage affects deals, how minority recapitalizations work, how due diligence differs between financial and strategic buyers, and how rollover equity can create or destroy value depending on structure. That is also where ongoing resources from Legacy Advisors can help, including related educational content and insights from the Legacy Advisors platform.
The main takeaway is simple. When PE buyers say platform, add-on, and buy-and-build, they are not speaking in abstractions. They are describing how they create returns, how they see your company, and what role they believe it can play inside a larger investment thesis. If you understand those terms, you understand more than vocabulary. You understand leverage, positioning, and what it takes to get a better outcome. If you are building with optionality in mind, now is the time to assess where your company fits, strengthen what buyers care about, and prepare before the market comes calling.
Frequently Asked Questions
What is a platform company in private equity, and why does it matter so much?
A platform company is the first business a private equity firm acquires in a specific investment thesis or industry segment. Think of it as the base that everything else will be built around. The private equity buyer is not just purchasing revenue and earnings; it is buying a leadership team, operating infrastructure, market position, systems, and a foundation strong enough to support future acquisitions. That is why the term “platform” carries more weight than simply “first deal.” It signals that the company is expected to anchor a broader growth strategy.
In practice, a platform usually has several characteristics buyers value: capable management, a scalable operating model, defensible customer relationships, stable cash flow, and enough size to absorb additional businesses without creating chaos. The buyer may plan to invest in sales, technology, recruiting, reporting systems, or geographic expansion to make the platform stronger over time. For founders, being labeled a platform company often means the buyer sees the business as strategically important and is willing to commit significant resources to grow it.
This matters because platform companies are often valued differently than smaller follow-on acquisitions. They may receive higher attention from buyers because they set the tone for the entire investment. The private equity firm will rely on the platform to integrate future add-ons, generate reporting, create synergies, and eventually help tell the growth story when the combined business is sold. In other words, when a buyer calls a company a platform, it usually means the business is not just being acquired for what it is today, but for the role it can play in building something much larger.
What does an add-on acquisition mean, and how is it different from a platform deal?
An add-on acquisition, sometimes called a bolt-on, is a company purchased after the platform acquisition to expand the overall business. Unlike the platform, the add-on is not intended to serve as the main operating foundation. Instead, it is typically folded into the existing platform to increase scale, enter new markets, add customers, broaden service lines, acquire talent, or strengthen capabilities. The platform is the hub; the add-on is brought into that hub to make the combined company more valuable.
The biggest difference is strategic role. A platform deal establishes the primary business the private equity firm will build around, while an add-on contributes to that strategy once the foundation is already in place. Because of that, buyers often evaluate add-ons through a somewhat different lens. They may focus heavily on how well the target fits with the platform, whether costs can be reduced after integration, whether cross-selling opportunities exist, and how quickly the acquired business can be absorbed into the larger company.
From a seller’s perspective, being sold as an add-on can feel different from being sold as a platform. In many cases, the acquired company will eventually adopt the platform’s systems, branding, reporting structure, and leadership model. Some founders remain involved, but often with a narrower scope than they would have had in a platform transaction. Add-ons can still command strong valuations, especially if they bring unique strategic value, but they are often priced in relation to their fit within the buyer’s larger plan rather than as standalone control investments. That is why understanding whether a buyer sees your business as a platform or an add-on is so important during sale discussions.
What is a buy-and-build strategy, and why do private equity firms use it?
Buy-and-build is a growth strategy in which a private equity firm acquires a platform company and then completes additional add-on acquisitions to create a larger, stronger, and more valuable enterprise. The idea is straightforward: instead of relying only on organic growth, the buyer accelerates expansion by combining multiple businesses under one ownership structure. This can increase revenue, improve market coverage, deepen expertise, strengthen negotiating leverage, and create operational efficiencies that no single company could achieve alone.
Private equity firms use buy-and-build because middle-market industries are often fragmented. That means many good businesses operate independently in the same sector, geography, or niche. By bringing them together, a buyer may be able to create a company with broader reach, more professional infrastructure, and greater strategic importance to future acquirers. In many cases, the value of the combined company becomes greater than the sum of its parts because of scale, better systems, unified leadership, shared services, and improved growth opportunities.
There is also a financial logic behind buy-and-build. Platform companies may trade at one valuation level, while smaller add-ons may be acquired at lower valuation multiples. If the buyer successfully integrates those businesses into a larger, higher-quality company, the resulting enterprise may later be sold at a stronger multiple. That multiple expansion, combined with earnings growth and synergy capture, is one of the reasons private equity firms pursue this model so aggressively. For founders, the practical takeaway is that buy-and-build is not just a buzzword. It is a deliberate strategy designed to transform a single acquisition into a scaled company that commands greater value at exit.
How do platform, add-on, and buy-and-build concepts affect a founder during a sale process?
These concepts affect everything from valuation expectations to post-closing responsibilities. If a buyer sees your company as a platform, you may be evaluated on leadership depth, systems, scalability, and your ability to help drive future acquisitions. The buyer is effectively asking, “Can this business serve as the backbone of a broader investment?” That can create opportunities for sellers who want to roll equity, remain active, and participate in the upside of future growth. It can also come with more scrutiny around management quality, financial reporting, technology, and operational readiness.
If your company is viewed as an add-on, the conversation may shift toward strategic fit. The buyer may care most about your customer base, geography, service capabilities, or niche expertise and how those assets complement an existing platform. In that situation, integration planning becomes especially important. Founders should understand what will happen to employees, branding, systems, decision-making authority, compensation structures, and their own role after closing. An add-on transaction can still be highly successful, but the future of the business is more likely to be shaped by the platform’s existing leadership and operating model.
Buy-and-build strategy also affects negotiations around timing and structure. A founder selling to a private equity-backed buyer may be asked to support integration, stay for a transition period, or roll some proceeds into the larger company. That can be attractive if the combined business grows meaningfully and is sold later at a premium. At the same time, founders should ask direct questions: Is this a platform or an add-on? What does the integration plan look like? Who will lead the combined company? What resources will the buyer invest? How will success be measured? Clear answers to those questions help sellers understand not only the purchase price, but the real future of the business after the deal closes.
Why do these private equity terms matter even if a founder is not planning to sell immediately?
They matter because they shape how sophisticated buyers evaluate readiness, value, and strategic position long before a sale process begins. A founder who understands what private equity buyers mean by platform, add-on, and buy-and-build can make better decisions about building the company. For example, if you want your business to be attractive as a platform, you may invest earlier in leadership, financial reporting, customer diversification, scalable systems, and repeatable processes. Those improvements not only make the business more sellable, but often make it stronger and more profitable in the meantime.
Even if your likely path is to become an add-on rather than a platform, understanding that role can still be useful. Buyers may place a premium on companies with unique capabilities, strong local market share, specialized service lines, recurring customers, or relationships that are hard to replicate. Knowing where your business fits in a likely consolidation strategy can help you prioritize growth initiatives and position the company more effectively. It also helps you recognize the difference between a buyer who truly sees strategic value and one who is simply fishing for a low-priced acquisition.
More broadly, these terms matter because private equity is a major force in middle-market M&A. Founders who understand the language can navigate conversations with more confidence, ask better questions, and avoid misunderstandings about valuation, control, and post-close expectations. Whether a sale is two months away or five years away, knowing how buyers think about platforms, add-ons, and buy-and-build strategies gives you a practical advantage. It allows you to prepare intentionally rather than reactively, which is often the difference between an average outcome and a very strong one.