

How Roll-Up Strategies Change the Value of Niche Market Leaders
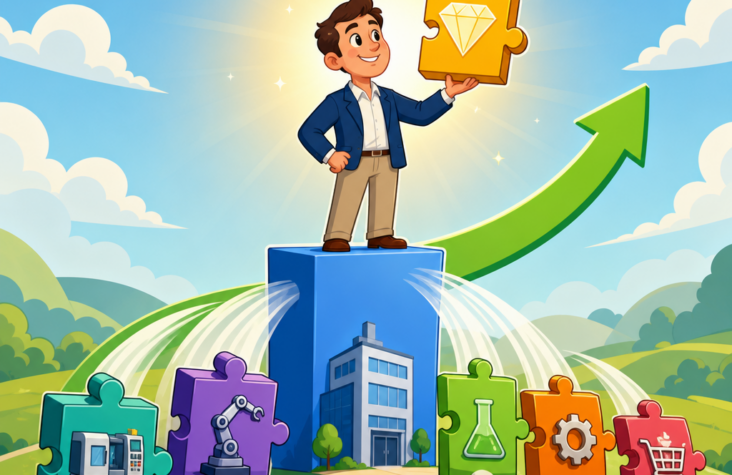
Roll-up strategies can dramatically increase the value of niche market leaders because they turn fragmented industries, inconsistent operations, and local brand strength into scalable platforms that private equity buyers, lenders, and strategic acquirers can underwrite with confidence.
For founders in specialized sectors, a roll-up strategy is not just an acquisition tactic. It is a value-creation framework. In practical terms, a roll-up means acquiring multiple businesses in the same industry or adjacent niches, integrating them under a shared operating model, and using scale to expand margins, market reach, and exit optionality. A niche market leader is a company with a defensible position in a narrow category, geography, customer segment, or service specialization. Think regional HVAC consolidators, specialty medical distributors, industrial safety trainers, managed IT firms focused on one vertical, or boutique marketing agencies dominant in one channel.
This matters because many niche leaders hit a valuation ceiling when they remain standalone businesses. They may be profitable, respected, and growing, but buyers often see concentration risk, founder dependence, limited scale, and a small addressable market. A well-executed roll-up changes that perception. It can shift the conversation from “small business with good cash flow” to “platform company with strategic scale.” I have seen this dynamic repeatedly in founder-led businesses: the same company that once traded on a modest EBITDA multiple becomes significantly more valuable when positioned as the anchor of a larger consolidation strategy.
As a hub for advanced strategies and case studies, this article explains how roll-ups change valuation, where they work best, what buyers and capital providers look for, which risks can destroy value, and how founders should think about timing. If you are building in a fragmented niche and wondering how private equity and capital markets evaluate your future, this is the framework.
Why niche markets are ideal for roll-up strategies
Roll-ups work best in fragmented industries where no single operator has dominant market share, customers buy repeatedly, and operations can be standardized without destroying the local advantage that made each business successful. Niche markets often fit that pattern perfectly. Thousands of founder-owned companies may operate in parallel, each with strong customer relationships but weak infrastructure, limited data, and no institutional succession plan.
Private equity firms are drawn to these markets for four reasons. First, fragmentation creates acquisition supply. If there are 2,000 owner-operated firms in a regionally dispersed sector, a platform has room to grow through tuck-in acquisitions. Second, recurring demand improves financing. Industries with maintenance contracts, recurring service schedules, replenishment buying, or mandated compliance work are easier to underwrite. Third, niche specialization often protects pricing better than generalized competition. Fourth, many sellers are succession-driven, which makes deal flow more realistic than in sectors dominated by venture-backed companies holding out for hypergrowth valuations.
Real-world examples make this easier to see. HVAC, home services, dental practices, veterinary clinics, wealth management RIAs, managed service providers, insurance brokerages, and industrial testing businesses have all seen aggressive consolidation because they combine recurring customer need with fragmented ownership. In each case, the “niche leader” may start as a local operator with a strong brand in one county, one state, or one vertical. The roll-up transforms that company into a platform.
How roll-ups change valuation mechanics
The biggest misconception founders have is that value rises simply because revenue rises. In roll-ups, valuation changes because the quality of earnings, transferability, and strategic relevance improve. A larger revenue base helps, but the real shift comes from multiple expansion and stronger cash flow.
A standalone niche leader may be valued primarily on trailing EBITDA, adjusted for owner compensation and a handful of add-backs. If the business depends on the founder, has customer concentration, and lacks depth in leadership, the buyer sees risk. That pushes the multiple down. In a roll-up, the platform can lower perceived risk and improve economics in ways that justify a higher multiple.
The first source of value is consolidated purchasing power. Combined entities can negotiate better with vendors, software providers, insurers, lenders, and logistics partners. The second is shared overhead. Accounting, HR, legal, recruiting, marketing systems, and finance can be centralized. The third is pricing sophistication. A larger platform usually has better data and tighter margin discipline than smaller founder-led firms. The fourth is cross-selling. If one acquired company serves hospitals and another serves ambulatory groups, the platform can package services across both.
The fifth, and often most important, source of value is multiple arbitrage. If small founder-owned businesses in a niche sell for lower multiples than a scaled platform in the same sector, acquiring many smaller firms and integrating them into a larger entity can create enterprise value beyond the simple sum of the parts. That does not mean easy money. It only works if integration is real and earnings quality is preserved.
| Valuation Factor | Standalone Niche Leader | Rolled-Up Platform |
|---|---|---|
| Buyer Perception | Local or founder-led business | Scalable platform with expansion path |
| EBITDA Quality | Often uneven and owner-adjusted | More normalized and institutional |
| Management Depth | Thin leadership bench | Layered leadership and functional heads |
| Revenue Mix | Concentrated by client or geography | Diversified across accounts and markets |
| Capital Access | Limited lender appetite | Stronger debt and equity interest |
| Likely Multiple | Lower due to risk and size | Higher due to scale and transferability |
What private equity looks for in a roll-up platform
Private equity does not just buy a company. It buys a thesis. In a roll-up, that thesis must be specific enough to finance and broad enough to scale. The initial platform company usually needs several traits: a respected position in its niche, strong retention, predictable cash flow, clean financial reporting, and a management team that can absorb acquisitions without operational collapse.
From experience, sponsors focus heavily on whether the platform can support integration. That means disciplined monthly reporting, clear unit economics, repeatable onboarding processes, and leadership that can make acquired owners productive rather than defensive. PE firms also want a realistic M&A pipeline. A founder saying “there are lots of businesses we could buy” is not enough. They want named targets, outreach patterns, broker relationships, and a documented rationale for why sellers would transact.
Capital markets also care about durability. If the niche depends on one regulation, one referral partner, or one unstable traffic source, the roll-up story weakens fast. That is why the best platforms sit in sectors with repeat demand and low technology disruption. They do not need to be glamorous. In fact, many of the best roll-up sectors are operationally boring and financially resilient.
Advanced strategies that make roll-ups work
The most successful roll-ups are not random buying sprees. They are disciplined operating strategies. One advanced approach is geographic density. Instead of buying firms all over the country, the platform dominates a corridor where route density, labor sharing, and brand awareness create immediate synergy. Another is service-line adjacency. A niche leader in one service can add complementary offerings through acquisitions, increasing share of wallet without abandoning its core.
A third strategy is leadership retention with clear economic alignment. Many founder-sellers want liquidity but still care about local teams and customers. Structured properly, equity rollover, stay bonuses, and performance incentives can turn sellers into productive operators inside the platform. A fourth strategy is system-first integration. The platform does not need to centralize everything on day one, but it must standardize data, reporting cadence, pricing logic, and key KPIs quickly.
I also favor a strategy many founders overlook: narrative discipline. Buyers pay more for businesses that can explain exactly why acquisitions create value. If management cannot articulate the integration model, synergy timeline, and post-close accountability structure, the roll-up looks speculative. If they can, the company feels institutional, and that has valuation consequences.
Case study patterns founders should understand
Across sectors, the same roll-up patterns repeat. In home services, local operators are often acquired because customer acquisition, dispatch, and technician utilization improve under scale. In healthcare services, fragmentation plus recurring demand plus compliance burdens make smaller operators more willing to join a better-capitalized platform. In professional services, fragmented client relationships become more valuable when paired with centralized business development and margin management.
One common pattern is the “category king” model. A niche leader dominates a very specific segment, such as compliance training for one industry or digital marketing for one vertical. The roll-up then acquires adjacent specialists, preserving niche expertise while creating a broader solution set. Another pattern is the “succession wave” model, where aging founders without internal successors create a sustained pipeline of acquisition opportunities.
The key lesson from these case studies is that niche expertise does not lose value in consolidation if the platform protects what made the target attractive. Buyers overpay when they assume all synergies are immediate. Operators underperform when they strip away local strengths too fast. The best roll-ups standardize infrastructure while preserving customer trust.
Risks that destroy roll-up value
Roll-ups fail when integration discipline fails. The biggest risk is overestimating synergies and underestimating cultural friction. If acquired teams leave, customers churn, or reporting remains inconsistent, the supposed platform is just a loose collection of businesses. That does not deserve a premium multiple.
Another risk is leverage. Many roll-ups are debt-supported. If earnings disappoint, interest rates rise, or acquisitions slow, the capital structure becomes restrictive. A third risk is poor target selection. Buying weak businesses because they look cheap almost always backfires. A fourth risk is founder overdependence at the platform level. If the entire strategy sits in one charismatic operator’s head, buyers discount the story.
There is also the issue of accounting integrity. Add-backs, earn-out assumptions, and integration adjustments can make a platform look better on paper than it is in reality. Serious buyers and lenders will cut through that. If you want platform valuation, you need platform-quality reporting.
How niche founders should position for a roll-up-driven exit
Even if you are not planning to become the acquirer yourself, understanding roll-ups can change how you build. The strongest niche leaders become attractive platforms or premium add-ons because they are clean, disciplined, and strategically clear. Start with financials. Monthly accrual-based reporting, normalized compensation, clear margins, and reliable KPIs matter. Next, reduce founder dependence. Build operating layers, document SOPs, and make customer relationships transferable.
Then think about your niche defensibility. Why do customers choose you? What makes your revenue stickier than peers? Which adjacent services, geographies, or target types make sense? Founders should also map the buyer landscape early. Which PE firms are active in your category? Which strategics are consolidating? Which independent sponsors are building themes around your niche?
This hub article exists because advanced strategy matters. Roll-up value is not just about buying more companies. It is about proving that your niche leadership can anchor something larger. That can mean becoming the platform, joining the right platform, or preparing your company so that when consolidators call, you negotiate from strength. If your business sits in a fragmented market and you want to understand how to increase value before an exit, start now: clean the books, build management depth, protect your margin, document your systems, and study how capital is moving through your niche. That is how roll-up strategies change the value of niche market leaders. And if you are serious about preparing for that kind of outcome, take the next step and build your plan.
Frequently Asked Questions
What is a roll-up strategy, and why does it matter so much for niche market leaders?
A roll-up strategy is the process of acquiring and combining multiple businesses within the same specialized industry to create a larger, more efficient, and more valuable platform. In niche markets, this matters because many industries are highly fragmented, with strong local operators, uneven systems, limited management depth, and inconsistent financial reporting. On a standalone basis, even an excellent niche business may be valued conservatively because buyers see concentration risk, geographic limits, owner dependence, or a lack of scale. A well-executed roll-up changes that equation.
By bringing together several businesses that serve similar customers or operate in adjacent territories, founders and investors can create a company that looks fundamentally different from the original standalone entity. The combined platform often has broader market coverage, more diversified revenue, stronger purchasing power, better staffing redundancy, and more predictable performance. That makes the business easier for private equity firms, lenders, and strategic acquirers to evaluate and finance. In other words, the roll-up converts local leadership into institutional-grade value.
For niche market leaders specifically, the strategy is powerful because it builds on what they already do well. They usually understand the customer, the pricing model, the service delivery process, and the competitive landscape better than outside buyers do. That industry knowledge becomes an advantage when identifying acquisition targets, integrating operations, and standardizing best practices. Instead of competing one location at a time, the company begins to behave like a scalable platform with repeatable systems and a stronger strategic narrative. That shift is often what drives a material increase in valuation.
How does a roll-up strategy increase the valuation of a niche business?
A roll-up strategy can increase valuation through both better financial performance and a change in how the market perceives the business. On the financial side, combining companies can improve margins through shared overhead, stronger vendor terms, centralized back-office functions, optimized staffing, and cross-selling opportunities. A larger company may also invest in technology, sales management, recruiting, or compliance in ways that smaller operators cannot justify on their own. As earnings improve and cash flow becomes more resilient, the value of the business rises.
Just as important, however, is the multiple expansion that often comes with scale. Small niche businesses are frequently valued at lower earnings multiples because they are seen as riskier and harder to transfer. They may depend heavily on a founder, operate in only one market, or lack reporting sophistication. A consolidated platform with multiple locations, a broader customer base, and a professional management team can attract a different class of buyer. That buyer may be willing to pay a meaningfully higher multiple because the business is now larger, more diversified, and easier to underwrite.
There is also a strategic premium associated with market position. When a company becomes one of the few scaled players in a fragmented niche, it can command attention from larger financial and strategic buyers who want entry into the sector without building from scratch. The result is that value is created not only by adding revenue and EBITDA from acquired businesses, but by transforming the company into a more attractive asset. In many cases, the most significant increase in value comes from that transformation rather than from cost savings alone.
Why are fragmented industries especially attractive for roll-up strategies?
Fragmented industries are especially attractive because they contain many small operators with similar offerings but inconsistent execution, limited capital, and varying levels of professionalism. That environment creates an opening for a disciplined buyer to acquire businesses at reasonable prices and then improve them under a unified platform. In a fragmented market, no single competitor may have enough scale to set the standard, which means a consolidator can build that standard over time and become the category leader.
These industries also tend to offer a large pool of potential acquisition targets. Many founders are approaching retirement, lack succession plans, or want liquidity but still care about the legacy of their businesses. A roll-up strategy can appeal to those sellers because it offers a path to join a larger organization that preserves customer relationships and employee opportunities while giving the owner a way to transition. For the acquiring platform, this creates a repeatable pipeline rather than a one-off deal environment.
From a value-creation standpoint, fragmentation usually means inefficiencies are everywhere. Different businesses may be using separate software systems, paying different supplier prices, handling hiring and scheduling manually, or missing opportunities to upsell customers across locations. A sophisticated platform can unify these functions, improve visibility into performance, and replicate the strongest operating practices across the portfolio. In highly specialized sectors, even modest process improvements can have an outsized impact because the baseline is often so uneven. That is why fragmented markets are often the ideal terrain for a roll-up strategy.
What makes a roll-up successful instead of just a collection of acquisitions?
A successful roll-up is not defined by the number of deals completed. It is defined by whether the combined business becomes more valuable, more efficient, and more strategically compelling than the individual companies were on their own. That requires a clear integration playbook. Acquiring businesses without a plan for financial reporting, leadership alignment, technology migration, branding decisions, pricing discipline, and cultural integration can create complexity faster than value. The best roll-ups treat integration as a core operating capability, not an afterthought.
Leadership and infrastructure are critical. A niche market leader needs strong post-acquisition processes for onboarding new companies, retaining key managers, standardizing metrics, and preserving customer relationships. It also needs to know where standardization matters and where local flexibility should remain. In many specialized sectors, local brand trust, technician relationships, or regional sales knowledge are part of what made the acquired company successful in the first place. A smart roll-up does not erase those strengths. It builds common systems underneath them while preserving what customers actually value.
Discipline in target selection matters just as much. The most effective acquirers do not buy every available business. They focus on targets that strengthen geography, expand customer density, add talent, deepen a service line, or improve strategic positioning. They also pay close attention to quality of earnings, customer concentration, legal exposure, and the true level of owner dependence. When acquisitions fit a coherent strategy and integration is handled well, the company becomes more than the sum of its parts. That is the difference between a successful roll-up and a loose collection of businesses held together only by ownership.
What should founders of niche market leaders think about before pursuing a roll-up strategy?
Founders should start by asking whether their business can serve as a credible platform. That means evaluating the strength of their management team, the quality of their financial reporting, the repeatability of their operating model, and their ability to integrate other companies without disrupting current performance. If the business still relies too heavily on the founder for sales, delivery, or daily decision-making, scaling through acquisitions may expose weaknesses rather than create value. Building a platform usually requires institutional habits before institutional scale appears.
They should also think carefully about the end goal. Some founders pursue roll-ups to create a larger enterprise for long-term ownership, while others want to build toward a recapitalization or sale to private equity or a strategic buyer. That distinction affects deal structure, pace of acquisitions, leverage tolerance, and integration priorities. A founder who understands the likely future buyer can make better decisions about reporting standards, governance, management depth, and which synergies to prioritize. In practical terms, value is often maximized when the company is built in a way that a future acquirer can underwrite with confidence.
Finally, founders need to be realistic about execution risk. Roll-ups can create substantial value, but they require capital discipline, patience, and operational rigor. Cultural mismatches, weak diligence, overpayment, poor integration, or excessive debt can undermine the strategy quickly. The upside is real, but so is the complexity. For founders in specialized sectors, the opportunity is often worth pursuing because they possess market insight others do not. The key is to approach the roll-up not merely as a series of deals, but as a deliberate value-creation framework designed to turn a strong niche business into a scalable market leader.