


Business Services M&A: Why Fragmented Niches Continue to Consolidate
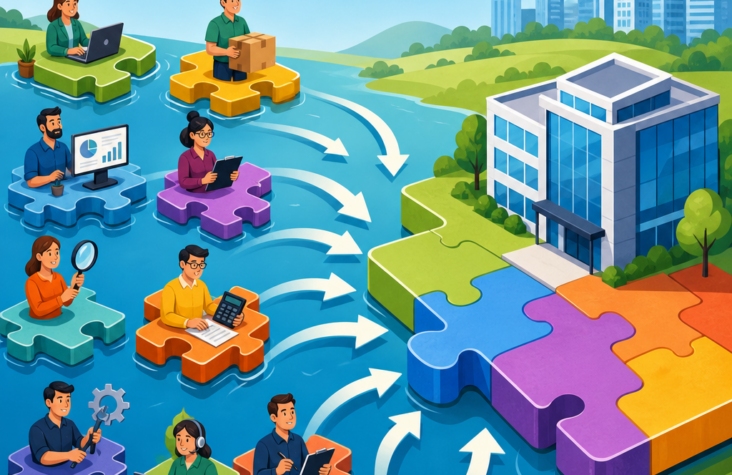
Business services M&A continues to accelerate because fragmented niches create a rare combination of recurring revenue, operational inefficiency, and scalable upside that sophisticated buyers know how to unlock. In simple terms, fragmentation means no single company controls much market share, even though the market itself is large, durable, and often essential to how other companies operate. Business services is a broad category that includes accounting firms, marketing agencies, IT managed service providers, HR and payroll companies, commercial cleaning, facilities management, engineering consultancies, staffing firms, compliance providers, and many other specialized operators. Consolidation is the process of combining many smaller businesses into larger platforms through acquisition. That process matters because it changes valuations, buyer behavior, competitive dynamics, and the strategic options available to founders. I have worked with founders preparing for sale and with buyers evaluating platforms, and the pattern is consistent: niches consolidate when scale produces measurable economic advantages. Those advantages include stronger margins, lower customer acquisition costs, better purchasing power, broader geographic reach, and deeper management infrastructure. For business owners, this trend can create exceptional exit opportunities, but it also raises the bar. Buyers pay premium valuations for companies that are transferable, professionally run, and positioned inside sectors with favorable tailwinds. For readers exploring sector-specific spotlights, this article serves as the hub: a comprehensive map of why consolidation continues, which subsectors attract the most buyer interest, what acquirers look for, and how founders should interpret the market now.
Why fragmented business services sectors attract M&A capital
Fragmented markets attract acquirers because fragmentation usually signals that value can be created through organization, not just invention. In many business services niches, thousands of local or regional firms deliver similar services with inconsistent branding, uneven technology adoption, and limited back-office sophistication. That creates an opening for a well-capitalized buyer to assemble a larger, more efficient platform. Private equity firms especially like this model because they can buy a strong initial platform, then add smaller tuck-in acquisitions at lower multiples, integrate operations, and eventually sell the larger combined business at a premium.
Several underlying characteristics make these sectors especially attractive. First, many services are non-discretionary. Companies may reduce spend in a downturn, but they still need payroll, tax support, IT security, regulatory compliance, staffing, facilities support, and revenue generation. Second, many services have recurring or repeat revenue. A managed IT provider billing monthly support fees, a payroll processor with annual contracts, or a commercial landscaping company on recurring maintenance schedules offers predictability that buyers reward. Third, most fragmented service sectors still have a long runway for professionalization. The gap between a founder-led firm and an institutionally scaled operator remains wide in many categories.
Named concepts matter here. Buyers often pursue a buy-and-build strategy, where the first acquisition becomes the platform company and later acquisitions expand density, capabilities, or geography. They also look for economies of scale, meaning fixed costs like leadership, software, finance, recruiting, and insurance can be spread across a larger revenue base. In practical terms, a $5 million EBITDA platform can support a stronger executive team than five separate $1 million EBITDA companies. That difference alone can transform growth rates and exit value.
What continues to drive consolidation across business services
Consolidation persists because the strategic logic keeps improving. Labor remains expensive, technology keeps raising customer expectations, and buyers still see arbitrage between what small firms trade for and what larger integrated platforms can command. A founder-owned agency or consulting firm may be valued on a lower EBITDA multiple because it depends heavily on the owner. Once folded into a broader platform with stronger systems, diversified leadership, and cross-sell opportunities, the combined business may command a higher multiple. That spread is one of the engines of modern business services M&A.
Technology is also a force multiplier. Cloud software, workflow automation, AI-assisted service delivery, and centralized CRM systems make it easier to integrate previously independent firms. Twenty years ago, rolling up local service operators could become an administrative mess. Today, acquirers can centralize finance in NetSuite, standardize sales in HubSpot or Salesforce, deploy project management systems like Asana or Monday.com, and benchmark performance across locations in near real time. Integration still takes skill, but the toolset is far better.
Demographics matter too. In many service categories, especially accounting, insurance services, engineering, and specialty consulting, a large share of founders are nearing retirement. Many built strong businesses but do not have internal successors. That creates supply. On the demand side, private equity dry powder, family office capital, and strategic acquirers all need quality assets. When you combine seller succession needs with buyer demand and scalable integration tools, consolidation becomes less of a temporary wave and more of a structural trend.
Sector-specific spotlights: the niches buyers watch most closely
The business services universe is broad, but some niches consistently attract more M&A attention than others because they combine recurring demand, fragmentation, and margin expansion potential. Managed IT services and cybersecurity remain active because digital infrastructure is mission-critical and customer contracts often renew. Accounting and tax services attract buyers because trust, retention, and regulatory complexity create defensible revenue. HR outsourcing, payroll, and benefits administration appeal to buyers for similar reasons: recurring relationships, embedded workflows, and cross-sell opportunities.
Marketing services continues to consolidate, especially performance marketing, CRM implementation, Amazon marketplace management, influencer services, and specialized B2B demand generation. The key distinction is that buyers prefer agencies with niche positioning, process discipline, and a path beyond pure founder relationships. Staffing and recruiting is another major spotlight, though buyer appetite shifts by vertical. Healthcare staffing, technical staffing, and executive search often draw stronger interest than generalized temp labor because margins and specialization tend to be better. Compliance, testing, inspection, and certification services also remain highly attractive because regulation tends to make revenue sticky.
Facilities and field services represent another durable area. Commercial cleaning, HVAC services, fire and life safety, landscaping, pest control, and property maintenance all benefit from route density, recurring service schedules, and local fragmentation. Engineering, environmental consulting, and specialty advisory firms draw attention when they have strong utilization, long client tenure, and defensible sector expertise. The common thread across these sector-specific spotlights is not glamour. It is repeatability, resilience, and room for operational improvement.
| Sector | Why Buyers Care | Common Risks | Typical Value Drivers |
|---|---|---|---|
| Managed IT & Cybersecurity | Recurring contracts, mission-critical service, cross-sell potential | Customer concentration, talent retention, tool sprawl | Monthly recurring revenue, low churn, security expertise |
| Accounting & Tax | Sticky clients, regulatory demand, succession-driven supply | Partner dependence, capacity constraints, aging workforce | Retention, niche expertise, scalable staffing model |
| Marketing Agencies | Niche specialization, measurable ROI, service bundling | Founder-led sales, volatile clients, low margins | Recurring retainers, vertical focus, strong delivery systems |
| Staffing & Recruiting | Fragmented market, repeat demand, sector specialization | Economic cyclicality, concentration, recruiter turnover | Gross margin, niche focus, client diversification |
| Facilities & Field Services | Route density, recurring work, local roll-up potential | Labor intensity, insurance costs, inconsistent service quality | Contract renewals, density, branch-level efficiency |
| Compliance & Specialty Advisory | Regulatory tailwinds, sticky workflows, defensible expertise | Key expert reliance, changing rules, slow sales cycles | Embedded relationships, certifications, niche authority |
How buyers evaluate business services platforms and add-ons
Not all service companies are evaluated the same way. Buyers distinguish sharply between platform investments and add-on acquisitions. A platform is the anchor asset: larger, more mature, and capable of supporting future acquisitions. An add-on is a smaller company that expands geography, customers, talent, or capabilities. This distinction matters because platform companies often earn materially higher multiples.
What gets a business treated like a platform? Usually a combination of scale, management depth, clean financial reporting, diversified revenue, and professional systems. Buyers want monthly financials prepared consistently, normalized EBITDA, clear customer cohorts, low concentration, and visible sales performance. They also want founder dependency reduced. If the founder is the only rainmaker, service architect, and relationship manager, the buyer sees risk. If the business has a president, sales leader, delivery lead, and controller who can run the operation, valuation usually improves.
Quality of revenue is central. In diligence, buyers look closely at retention, contract structure, revenue by customer, gross margin by service line, and labor utilization. They want to know if customers are truly recurring or just repeat by habit. They also test whether price increases stick, whether revenue is project-based or contractual, and whether growth comes from sustainable channels. For service firms, customer concentration and employee concentration can be as important as EBITDA itself.
Why some niches consolidate faster than others
Not every business services niche consolidates at the same speed. The fastest-consolidating sectors usually share four traits: high fragmentation, measurable recurring revenue, low technological obsolescence, and clear synergies from scale. Managed services, payroll, route-based services, and compliance-heavy niches fit that profile well. By contrast, highly bespoke consultancies or talent businesses centered around one rainmaker may attract buyer interest but consolidate more slowly because integration is harder and transferability is weaker.
Regulation can accelerate consolidation. In environmental services, healthcare compliance, or cybersecurity consulting, changing rules increase the value of scale because larger firms can afford specialized expertise and better systems. Customer procurement behavior also matters. Larger enterprise buyers often prefer vendors with broader geographic coverage, stronger security standards, and formal reporting capabilities. That preference pushes smaller operators either to scale up or become acquisition targets.
Labor intensity can work both ways. It may slow consolidation when margins are thin and turnover is high, but it can also drive roll-ups when acquirers believe better recruiting, training, routing, or software can dramatically improve results. That is why field services remain active despite execution complexity. Sophisticated buyers are not avoiding labor-heavy businesses; they are selecting the ones where discipline and density create advantage.
What this means for founders, owners, and investors
For founders, the consolidation trend creates opportunity, but not automatically. The market rewards preparation. If you operate in a fragmented niche with active M&A, that does not guarantee a premium exit. It means you have a chance to earn one if your business is buyer-ready. In practical terms, that means clean accrual-based financials, documented processes, realistic forecasts, diversified revenue, and a management structure that lowers reliance on you. It also means understanding whether your company is more likely to be valued as a platform or an add-on.
For investors, sector-specific spotlights matter because not all fragmented niches are equally durable. A niche can be fragmented and still unattractive if customer churn is high, revenue is too project-based, or labor economics are deteriorating. The best areas combine stickiness, defensibility, and the ability to professionalize quickly. For strategic buyers, the question is often adjacency: which niche extends our current customer value proposition? For private equity, the question is usually repeatability: can this be rolled up and improved systematically?
One important nuance is that consolidation does not always help every seller at every moment. If too many similar businesses come to market at once, buyers can become more selective. If interest rates rise, leveraged buyers may reduce prices or focus on larger, cleaner assets. If AI or automation changes service delivery in a niche, buyers may pause while they re-evaluate labor models. Fragmentation invites consolidation, but timing and preparation still determine outcomes.
Where business services M&A is likely headed next
The next phase of business services consolidation will likely be shaped by three forces: AI-enabled efficiency, continued succession-driven supply, and more sophisticated buyer segmentation. AI will not eliminate most business services niches, but it will change cost structures, staffing models, and buyer expectations. Service firms that use automation to improve margin without eroding quality will become more attractive. Succession will remain powerful, especially in founder-led professional services where internal transition is hard. And buyers will continue segmenting markets more finely, rewarding specialists over generalists.
Expect more activity around businesses that combine service revenue with workflow software, proprietary data, or deeply embedded customer relationships. Expect more roll-ups in under-digitized local and regional niches. Expect more scrutiny around margin quality and team durability. Buyers still want growth, but they increasingly want proof that growth can survive leadership transition and technology disruption.
Business services M&A will continue because fragmented niches still offer one of the clearest playbooks in the market: buy quality companies, professionalize operations, expand density and capabilities, and create a larger asset worth more than the sum of its parts. For founders, that is the real benefit of understanding this trend. It helps you see your company not just as a service business, but as a strategic asset that can be built for optionality. If you operate in one of these sectors, now is the time to study buyer behavior, strengthen your fundamentals, and prepare early. The businesses that win in consolidating markets are usually the ones that were ready before everyone else noticed.
Frequently Asked Questions
Why are fragmented business services niches so attractive to M&A buyers?
Fragmented business services niches are attractive because they combine stable demand with unusually strong room for improvement. In a fragmented market, hundreds or even thousands of smaller operators may compete for customers, but no single company holds enough market share to define the category. That creates an opportunity for buyers to build scale in a way that is often much harder in already-consolidated industries. Many business services firms also benefit from recurring or repeat revenue, long client relationships, and services that are essential to day-to-day operations, which makes their cash flow profile especially appealing to private equity firms, strategic acquirers, and other sophisticated investors.
Buyers are also drawn to the operational upside. In many fragmented niches, individual firms are well run from a client-service perspective but underdeveloped in areas such as technology, pricing discipline, sales management, reporting, procurement, and back-office efficiency. An acquirer with experience, capital, and a playbook for integration can often improve margins without changing the core value delivered to clients. That is one of the main reasons business services M&A continues to accelerate: buyers are not only purchasing current earnings, they are buying the potential to professionalize operations and create a more valuable platform over time.
What does “fragmentation” actually mean in the context of business services M&A?
In practical terms, fragmentation means the market is large but highly divided among many smaller competitors. No single company has enough share to dominate the sector, even though the underlying services may be essential, recurring, and economically important. This is common across broad areas of business services, including accounting, marketing services, IT managed services, HR outsourcing, compliance support, and many specialized B2B service categories. A fragmented niche may have strong customer demand and healthy margins, yet still lack scaled operators with national reach, standardized delivery models, or modern technology infrastructure.
From an M&A perspective, fragmentation matters because it creates a clear path to consolidation. A buyer can acquire a strong platform company, then add smaller businesses that expand geography, capabilities, customer relationships, or sector expertise. Over time, that roll-up can produce a business with greater density, stronger pricing power, better cross-selling opportunities, and more efficient operations. The appeal is not simply that there are many targets available; it is that combining those targets thoughtfully can create a company worth materially more than the sum of its parts.
Why do recurring revenue and essential services matter so much in business services deals?
Recurring revenue is one of the most important drivers of value in business services M&A because it makes future performance more visible. Buyers place a premium on businesses that can reliably generate revenue month after month or year after year through retainers, managed services contracts, repeat engagements, or compliance-driven work. That consistency reduces perceived risk and supports stronger valuations, especially when customer retention is high and revenue is diversified across many clients rather than concentrated in a few accounts.
Essential services matter for a similar reason. When a service is closely tied to a client’s operations, regulatory obligations, financial reporting, infrastructure, or revenue generation, it becomes difficult to replace or eliminate. Businesses may delay discretionary spending in uncertain markets, but they usually continue to pay for the services they need to function properly. That resilience is highly attractive in an acquisition context. It gives buyers confidence that demand can hold up across economic cycles while also creating a foundation for upselling adjacent services, improving client lifetime value, and supporting long-term integration strategies.
How do buyers create value after acquiring companies in fragmented business services sectors?
Value creation typically comes from a combination of operational improvement, strategic expansion, and scale benefits. After an acquisition, buyers often focus on standardizing systems, centralizing administrative functions, improving KPI reporting, and introducing more disciplined sales and pricing processes. In many smaller service businesses, these capabilities are limited because founders have spent most of their energy on client delivery rather than building institutional infrastructure. A sophisticated acquirer can bring better processes, stronger management resources, and technology investments that improve efficiency and profitability.
Buyers also create value by broadening the company’s reach and offerings. Acquisitions can open new geographies, deepen expertise in a vertical market, or add complementary services that can be cross-sold to existing customers. In business services, this can be especially powerful because trust-based client relationships often support expansion into adjacent needs. A company that starts with one core service may be able to add advisory, implementation, analytics, compliance, or support capabilities over time. As the platform grows, it can benefit from stronger brand credibility, better recruiting, more purchasing leverage, and a larger base over which to spread fixed costs. All of that can support both earnings growth and multiple expansion.
What should owners of business services firms understand before considering a sale in a consolidating market?
Owners should understand that buyers are evaluating far more than revenue size. In a consolidating market, acquirers want to see high-quality earnings, strong customer retention, differentiated capabilities, and a business model that can integrate well into a larger platform. They will also examine client concentration, employee retention risk, margin profile, contract structure, and the extent to which performance depends on the founder personally. A company may operate in an attractive niche, but if processes are informal or too much knowledge sits with one person, buyers may view the opportunity as riskier and price it accordingly.
It is also important for owners to recognize that timing and preparation can materially influence outcomes. Firms that invest in clean financial reporting, documented workflows, scalable management structures, and clear growth strategies tend to attract broader buyer interest and stronger deal terms. In many cases, the best transactions occur when a company can show both current stability and future upside. That is exactly what buyers seek in fragmented business services categories: a solid base of recurring, essential revenue paired with meaningful opportunity for operational improvement and scaled growth. Owners who understand that buyer mindset are usually in a much better position to negotiate value and choose the right partner.