

Seller Due Diligence Checklist for Middle-Market Companies
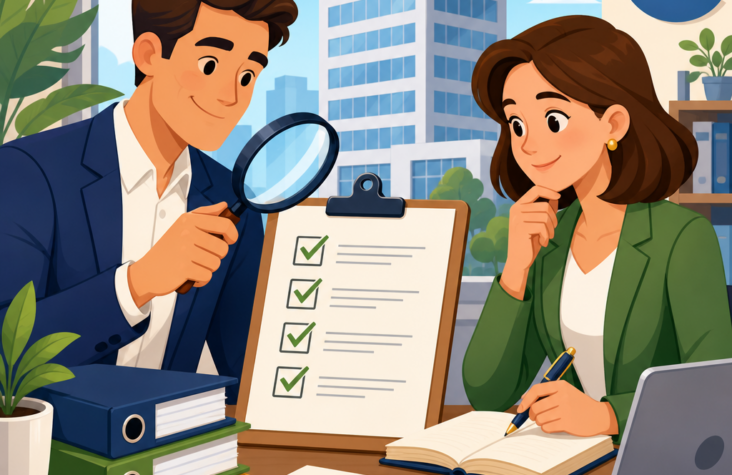
Seller due diligence is the internal review a middle-market company completes before going to market so management can identify risks, organize records, answer buyer questions quickly, and protect valuation during deal execution. For founders, owners, and executive teams, this step matters because buyers will scrutinize every financial statement, contract, policy, tax filing, and operational dependency once a letter of intent is signed. If the seller finds issues first, those issues can often be fixed, explained, or framed properly. If the buyer finds them first, the result is usually retrading, delayed closing, expanded indemnities, or a failed transaction. In the middle market, where companies often have between $10 million and $250 million in revenue and rely on a founder, a small leadership bench, or a concentrated customer base, seller due diligence becomes one of the most important value-protection tools available. I have seen well-run companies lose leverage simply because documents were scattered, EBITDA adjustments were poorly supported, or key contracts were unsigned. A disciplined seller due diligence checklist prevents that. It turns a reactive process into a controlled one, gives management a clear path to readiness, and creates a stronger story for buyers, lenders, quality of earnings providers, and legal counsel.
Why seller due diligence matters before buyers start asking questions
Seller due diligence matters because middle-market deals move from excitement to scrutiny very quickly. A buyer may love the growth story, customer list, margins, or market position, but once diligence begins, enthusiasm gets tested by facts. Buyers want proof that reported earnings are real, contracts are enforceable, taxes are current, systems are reliable, and the company can operate without unusual founder intervention. In practical terms, seller due diligence reduces surprises and shortens the distance between indication of interest and close. It also improves bargaining power because a prepared seller answers requests quickly, supports adjustments with evidence, and projects credibility throughout the process.
Preparation also affects timing. In many transactions, the diligence clock is compressed after exclusivity begins. If a seller waits until the buyer sends a request list, management can get buried in document gathering while still trying to run the company. That pressure leads to incomplete responses, inconsistent explanations, and unnecessary stress across the finance, legal, HR, and operations teams. A seller due diligence checklist avoids that trap by assigning tasks in advance, identifying outside advisors early, and building a data room before the first buyer meeting. Companies that do this tend to maintain momentum and preserve optionality longer.
Financial diligence checklist items every middle-market seller should address
Financial readiness is the center of any seller due diligence checklist because value is usually anchored to EBITDA, cash flow, or recurring revenue quality. Start with three years of monthly and annual financial statements, including profit and loss statements, balance sheets, and cash flow statements. Reconcile them to tax returns and general ledger reports. If there are material variances, document why. Buyers and quality of earnings firms will test whether management reporting ties to filed returns and audited or reviewed statements where available.
Normalize earnings carefully. Middle-market owners often discuss adjusted EBITDA, but every add-back must be specific, supportable, and nonrecurring. Owner compensation above market, one-time legal expenses, unusual consulting projects, nonoperating personal expenses, or discontinued initiatives may be valid adjustments. Each one should be listed in a schedule with invoices, payroll records, contracts, or board approvals behind it. Unsupported adjustments damage trust quickly. The same is true for working capital. Review aging reports for accounts receivable and accounts payable, identify slow-moving or obsolete inventory, and understand how seasonality affects the business. A buyer will use working capital targets in the purchase agreement, so the seller should know what “normal” looks like before negotiations begin.
Other core financial checklist items include debt schedules, capital expenditure history, budget-to-actual reporting, customer and product profitability, backlog, deferred revenue, and concentration analysis. If one customer represents 20 percent of sales, that fact is not automatically fatal, but management needs a clear explanation of relationship durability, contract terms, and retention history. If margins shifted meaningfully over the past twelve months, be ready to explain whether the cause was pricing, freight, labor, supply chain changes, or product mix.
Legal, tax, and compliance documents that must be organized early
Legal diligence is where many middle-market sellers discover preventable problems. The seller due diligence checklist should include organizational documents, stock ledgers, capitalization records, board and shareholder consents, entity charts, assumed names, and good standing certificates. If the company completed acquisitions, restructurings, or equity issuances over the years, confirm that all supporting records are complete. Missing approvals or unclear ownership chains create friction late in the process.
Material contracts deserve special attention. Gather customer agreements, supplier agreements, leases, loan documents, guarantees, software licenses, distributor arrangements, independent contractor agreements, employment agreements, and any contracts with change-of-control provisions. Buyers want to know whether a sale triggers consent rights, termination rights, or pricing resets. In founder-led businesses, I often find important relationships governed by expired contracts, unsigned renewals, or email understandings. Those issues should be cleaned up before going to market whenever possible.
Tax diligence should cover federal, state, local, and international filings if relevant. Organize income tax returns, sales and use tax filings, payroll tax records, nexus studies, correspondence with taxing authorities, and any open audits or payment plans. For middle-market companies that expanded across states or through ecommerce, sales tax exposure is a frequent diligence issue. It is far better to quantify exposure and address it early than let a buyer discover it during diligence. Also review unclaimed property, transfer pricing where applicable, and any tax credits or net operating losses being presented as part of the value story.
Operational, commercial, and customer diligence priorities
Operational diligence tests whether the company’s results are repeatable. A complete seller due diligence checklist should document how the business actually functions day to day. That includes process maps, standard operating procedures, facility summaries, production capacity, quality control metrics, safety records, major equipment lists, maintenance logs, cybersecurity protocols, disaster recovery plans, and ERP or accounting system descriptions. Buyers are not only evaluating what the business earned yesterday. They are evaluating whether it can keep earning tomorrow without hidden fragility.
Commercial diligence focuses on customers, channels, pricing, and market position. Sellers should prepare customer retention data, top account summaries, win-loss trends, sales pipeline reports, pricing policies, rebate or discount structures, churn analysis for recurring models, and major sales channel economics. For service businesses, explain utilization, realization rates, client tenure, and renewal patterns. For manufacturers and distributors, show order history, backlog quality, fill rates, and supply chain resilience. For software or tech-enabled companies, organize ARR or MRR reports, cohort data, churn, expansion revenue, and product roadmap materials.
This is also the right stage to pressure-test the management narrative. If the company is being marketed as recession-resilient, prove it with customer retention and margin performance through prior downturns. If it is being marketed as scalable, show operating leverage, hiring plans, and systems readiness. If it is being marketed as a platform acquisition, demonstrate cross-sell opportunity, geographic expansion potential, or tuck-in compatibility. Good seller due diligence aligns data with the story management intends to tell.
Human capital, leadership depth, and founder dependency review
One of the most important due diligence and deal execution resources for sellers is a clear talent review. Buyers know that middle-market companies often depend heavily on a founder or a handful of senior leaders. The seller due diligence checklist should therefore include an organization chart, employee census, compensation schedules, bonus plans, commission structures, equity or phantom equity arrangements, retention plans, and summaries of key roles. Identify who owns customer relationships, pricing authority, operations oversight, compliance management, and financial reporting.
Employment matters should be organized well before buyer review. Gather offer letters, confidentiality agreements, invention assignment agreements where relevant, restrictive covenant agreements, employee handbooks, benefit plans, immigration records if applicable, workers’ compensation history, and any pending or threatened HR claims. If there are known compensation inconsistencies, classification issues, or policy gaps, address them before diligence. Buyers do not expect perfection, but they do expect informed management and prompt responses.
Founder dependency deserves brutal honesty. If the owner approves every large quote, negotiates every key contract, or personally resolves customer disputes, that dependency will affect structure even if it does not affect price. Buyers may require a longer transition period, an earnout, or heavier management retention measures. Sellers who want the best terms should reduce that risk in advance by delegating authority, documenting processes, and elevating the leadership bench. This is one reason pages like Legacy Advisors emphasize preparation long before the sale process starts.
Data room preparation and request management during deal execution
A seller due diligence checklist is only effective if documents are organized into a usable data room. The best practice is to build a structured virtual data room before buyer outreach intensifies. At minimum, include sections for corporate records, financial statements, tax, legal, HR, customers, suppliers, operations, IT, insurance, environmental or regulatory materials, and real estate. Name files consistently, date them clearly, and remove duplicates. Sloppy data rooms create the impression of sloppy operations.
Access control matters too. Not every buyer should receive full information immediately. Sensitive customer lists, employee compensation details, or proprietary process materials may be staged as buyer seriousness increases. Your M&A advisor and legal counsel should help determine what gets shared when. Just as important, assign an internal response team. Typically that means a project lead, a finance lead, a legal point person, and operating leaders who can answer function-specific questions quickly. Centralize Q&A responses so the company answers consistently across buyers, lenders, and diligence providers.
If a quality of earnings review is expected, prepare for it early. Many middle-market processes now include buy-side QoE work almost automatically. Sellers who preempt that with a strong internal review, or in some cases a sell-side QoE, are better positioned to defend earnings and keep the process moving. This is especially useful when the company has complex revenue recognition, significant project accounting, multiple entities, or unusual working capital patterns.
Common middle-market diligence problems and how to fix them
The same issues appear repeatedly in middle-market deals. First, unsupported EBITDA add-backs. Fix this by documenting every adjustment with detail and evidence. Second, unsigned or expired customer and vendor contracts. Fix this by auditing key agreements and executing renewals where possible. Third, sales tax or payroll tax exposure. Fix this by involving tax counsel or a specialized CPA early and quantifying the issue. Fourth, founder dependency. Fix this by building management depth and transferring authority. Fifth, outdated cybersecurity or privacy controls. Fix this by implementing baseline policies, vendor reviews, and incident response procedures.
Another common issue is unrealistic forecasting. Sellers often present aggressive projections that are disconnected from historical performance or sales capacity. Buyers discount those quickly. A stronger approach is to build a defensible forecast tied to pipeline, pricing, staffing, margin assumptions, and known risks. It is better to present a credible model than an inflated one. I discuss this discipline often when speaking about exit planning and in The Entrepreneur’s Exit Playbook, because valuation is protected by credibility as much as by growth.
Finally, many sellers underestimate the importance of narrative consistency. The CIM, management presentation, financial model, legal disclosures, and buyer calls should all tell the same story. When numbers, contracts, and commentary align, buyers gain confidence. When they do not, retrading becomes much more likely.
How this hub supports due diligence and deal execution resources
This page is the hub for due diligence and deal execution resources because seller readiness is never one checklist item. It is a coordinated effort across finance, legal, tax, operations, HR, technology, and leadership. As you build out this subtopic, related articles should go deeper into quality of earnings preparation, LOI negotiation, working capital mechanics, management presentations, data room structure, customer concentration analysis, reps and warranties, founder transition planning, and post-close obligations. A good hub article helps readers see how those pieces fit together and gives them a practical entry point into action.
The central takeaway is simple. Seller due diligence is not a defensive chore. It is a strategic process that helps middle-market companies protect valuation, accelerate timelines, reduce surprises, and negotiate from a position of strength. If you are thinking about an exit in the next twelve to thirty-six months, start now. Build the checklist, assign owners, clean the records, pressure-test the story, and prepare the business as if buyers were already looking. They eventually will be. When that moment comes, the sellers who win are usually the sellers who prepared first. If you want to sharpen your readiness, review additional resources through Legacy Advisors and study the frameworks in The Entrepreneur’s Exit Playbook. Then start checking items off today.
Frequently Asked Questions
What is seller due diligence for a middle-market company, and why is it so important before going to market?
Seller due diligence is the internal review process a company completes before formally approaching buyers. For middle-market companies, it is essentially a full pre-sale readiness assessment covering financials, tax, legal, commercial operations, human resources, information technology, compliance, and key business risks. The goal is to understand exactly what a buyer will see, ask, and test once the sale process begins. Instead of waiting for diligence issues to surface under pressure after a letter of intent is signed, management proactively identifies gaps, inconsistencies, exposure areas, and documentation problems in advance.
This matters because buyers in the middle market are highly focused on risk transfer, earnings quality, cash flow durability, customer concentration, contract assignability, tax exposure, and operational dependencies. If problems are discovered late, they often affect price, deal structure, indemnity demands, escrow size, working capital negotiations, or closing timing. In some cases, late-stage surprises can cause retrading or even derail a transaction entirely. Seller due diligence helps management control the narrative by confirming what is accurate, correcting what is fixable, and preparing support for areas that require explanation.
It is also important because valuation is not driven only by growth and profitability. It is driven by confidence. A well-prepared seller that can produce organized records, reconcile financial performance, explain unusual trends, and answer buyer questions quickly tends to inspire more confidence and maintain momentum during the process. In practical terms, seller due diligence improves preparedness, reduces avoidable surprises, shortens response times in the data room, and gives the company a better chance of preserving valuation and negotiating leverage during deal execution.
What should be included in a seller due diligence checklist for a middle-market business?
A strong seller due diligence checklist should be broad enough to mirror the areas a buyer and its advisors will examine, but practical enough to prioritize the issues most likely to affect value and closing certainty. Financial materials are usually the starting point. This includes audited, reviewed, or internally prepared financial statements; monthly and annual reporting packages; general ledgers; trial balances; budget-to-actual reports; forecasts; revenue recognition policies; margin analyses; customer and product profitability; debt schedules; capital expenditure history; inventory reporting; aging reports for receivables and payables; and documentation supporting nonrecurring adjustments or add-backs.
Tax diligence is another major category. Sellers should gather federal, state, local, and, where applicable, international tax filings; sales and use tax documentation; payroll tax records; nexus analyses; correspondence with taxing authorities; net operating loss schedules; and support for any uncertain tax positions. Buyers will want to know whether returns were filed properly, whether taxes were paid on time, and whether there are exposures that could create post-closing liabilities.
Legal and corporate records should also be central to the checklist. This generally includes formation documents, bylaws or operating agreements, minute books, stock ledgers, capitalization records, equity grants, board approvals, material customer and supplier contracts, leases, loan agreements, guarantees, liens, litigation records, intellectual property registrations, data privacy policies, confidentiality agreements, employment agreements, non-competes, and any change-of-control or anti-assignment provisions that could complicate the sale.
Operational diligence should address how the business actually functions day to day. This often includes customer concentration analysis, supplier dependence, backlog reporting, pricing practices, churn and retention metrics, quality control procedures, manufacturing or service delivery workflows, facility matters, environmental issues, cybersecurity controls, IT systems, disaster recovery practices, insurance coverage, and management reporting processes. Human capital materials are also important, especially in founder-led or management-dependent businesses. Buyers will examine organizational charts, compensation structures, bonus programs, benefit plans, headcount trends, key employee retention risk, labor matters, and whether critical know-how is concentrated in only a few people.
The best checklist is not just a document request list. It is a risk-mapping tool. It should help management determine what is complete, what is missing, what needs cleanup, and what requires a proactive explanation before buyers raise the question themselves.
How far in advance should a company start seller due diligence, and who should be involved?
Most middle-market companies benefit from starting seller due diligence at least several months before going to market, and in more complex situations, even earlier. The right timing depends on the condition of the company’s records, the complexity of its legal structure, the quality of its monthly reporting, the number of states or countries where it operates, and whether there are known issues that need remediation. If the business has never been through a transaction process, if financial reporting is inconsistent, or if contracts and policies are scattered across departments, the preparation period may need to be longer.
Starting early creates options. Some issues can be corrected quickly, such as missing signatures, contract organization, account reconciliations, or policy updates. Others take more time, including tax cleanup, legal entity simplification, intellectual property assignments, customer contract amendments, audited financial statement preparation, or cybersecurity improvements. The more lead time management has, the more likely it is that those items can be resolved before they become negotiation leverage for a buyer.
As for participants, seller due diligence should be led internally by senior management, but it should not sit with one person alone. Finance usually coordinates the process because so much of buyer scrutiny starts with earnings, cash flow, balance sheet quality, and forecast credibility. Legal, HR, IT, operations, tax, and commercial leadership should also be involved because diligence questions cut across every function. In many middle-market transactions, the company’s investment banker, M&A counsel, accountants, and tax advisors also play key roles in helping prepare materials, identify risk areas, and frame disclosures appropriately.
The most effective process has clear ownership, deadlines, and escalation paths. Someone needs to decide what goes into the data room, who verifies accuracy, how open items are tracked, and how management will explain issues that cannot be fully fixed before launch. When handled this way, seller due diligence becomes a coordinated transaction readiness exercise rather than a last-minute scramble.
What are the most common issues buyers uncover during diligence that sellers should try to find first?
Buyers commonly find issues in a few repeat categories, and many of them are avoidable if the seller conducts a disciplined internal review first. One of the most frequent problems is weak financial support for adjusted EBITDA. Sellers may present add-backs for owner compensation, one-time expenses, or unusual costs, but if those adjustments are not clearly documented and consistently supported, buyers will challenge them aggressively. Similar issues arise when monthly reporting does not tie cleanly to annual statements or when margin trends, customer profitability, or working capital swings cannot be explained.
Another major area is customer and supplier concentration. A company may appear strong overall, but if a small number of customers drive a large share of revenue, or if a single supplier is critical to production or service delivery, buyers will focus on the stability of those relationships. Problems become more serious when contracts are informal, expired, not assignable, or contain termination rights tied to a change in control. Revenue quality concerns can also emerge if the business depends heavily on project timing, nonrecurring demand spikes, or pricing arrangements that are not contractually secure.
Tax and legal issues are also common. Buyers often uncover unfiled returns, sales tax exposure, payroll classification problems, undocumented related-party arrangements, missing board approvals, broken chains of intellectual property ownership, or contracts that were never properly executed. In founder-led businesses, personal and company expenses are sometimes intertwined in ways that create both tax and diligence complications. In people-intensive businesses, employment practices, bonus commitments, retention risk, or inconsistent restrictive covenant agreements can also become significant discussion points.
Operationally, buyers frequently identify overreliance on the founder, undocumented processes, weak cybersecurity controls, outdated insurance coverage, poor data retention practices, and the absence of formal compliance or policy frameworks. None of these issues automatically kills a deal, but each one can increase perceived risk. If the seller identifies them first, management can either correct them, quantify them, or prepare a credible explanation. That advance work often makes the difference between a manageable diligence discussion and a valuation issue.
How does seller due diligence help protect valuation and improve deal execution?
Seller due diligence protects valuation by reducing uncertainty. Buyers pay more when they believe the reported earnings are reliable, customer relationships are durable, contracts are enforceable, tax exposure is manageable, and the business can continue performing after the current owners transition. When a seller has already pressure-tested those areas internally, the company is better positioned to present a clear, well-supported investment case. That improves buyer confidence and can support stronger bids, narrower discounting for risk, and more competitive tension in the process.
It also improves deal execution by making the diligence phase faster and more controlled. Once a letter of intent is signed, the buyer’s team typically moves quickly and asks for a large volume of documents and explanations. If the seller is not prepared, management gets pulled into reactive fire drills, response quality suffers, and momentum slows. Delays create room for buyer skepticism and can weaken the seller’s negotiating position. By contrast, when records are organized, open issues are known, and explanations are already prepared, the company can respond efficiently and keep the process moving toward confirmatory diligence and